
Health Check: How Prudently Does Mingfa Group (International) (HKG:846) Use Debt?
Legendary fund manager Li Lu (who Charlie Munger backed) once said, 'The biggest investment risk is not the volatility of prices, but whether you will suffer a permanent loss of capital.' So it might be obvious that you need to consider debt, when you think about how risky any given stock is, because too much debt can sink a company. As with many other companies Mingfa Group (International) Company Limited (HKG:846) makes use of debt. But should shareholders be worried about its use of debt?
Why Does Debt Bring Risk?
Debt and other liabilities become risky for a business when it cannot easily fulfill those obligations, either with free cash flow or by raising capital at an attractive price. Ultimately, if the company can't fulfill its legal obligations to repay debt, shareholders could walk away with nothing. However, a more common (but still painful) scenario is that it has to raise new equity capital at a low price, thus permanently diluting shareholders. Of course, debt can be an important tool in businesses, particularly capital heavy businesses. When we examine debt levels, we first consider both cash and debt levels, together.
What Is Mingfa Group (International)'s Net Debt?
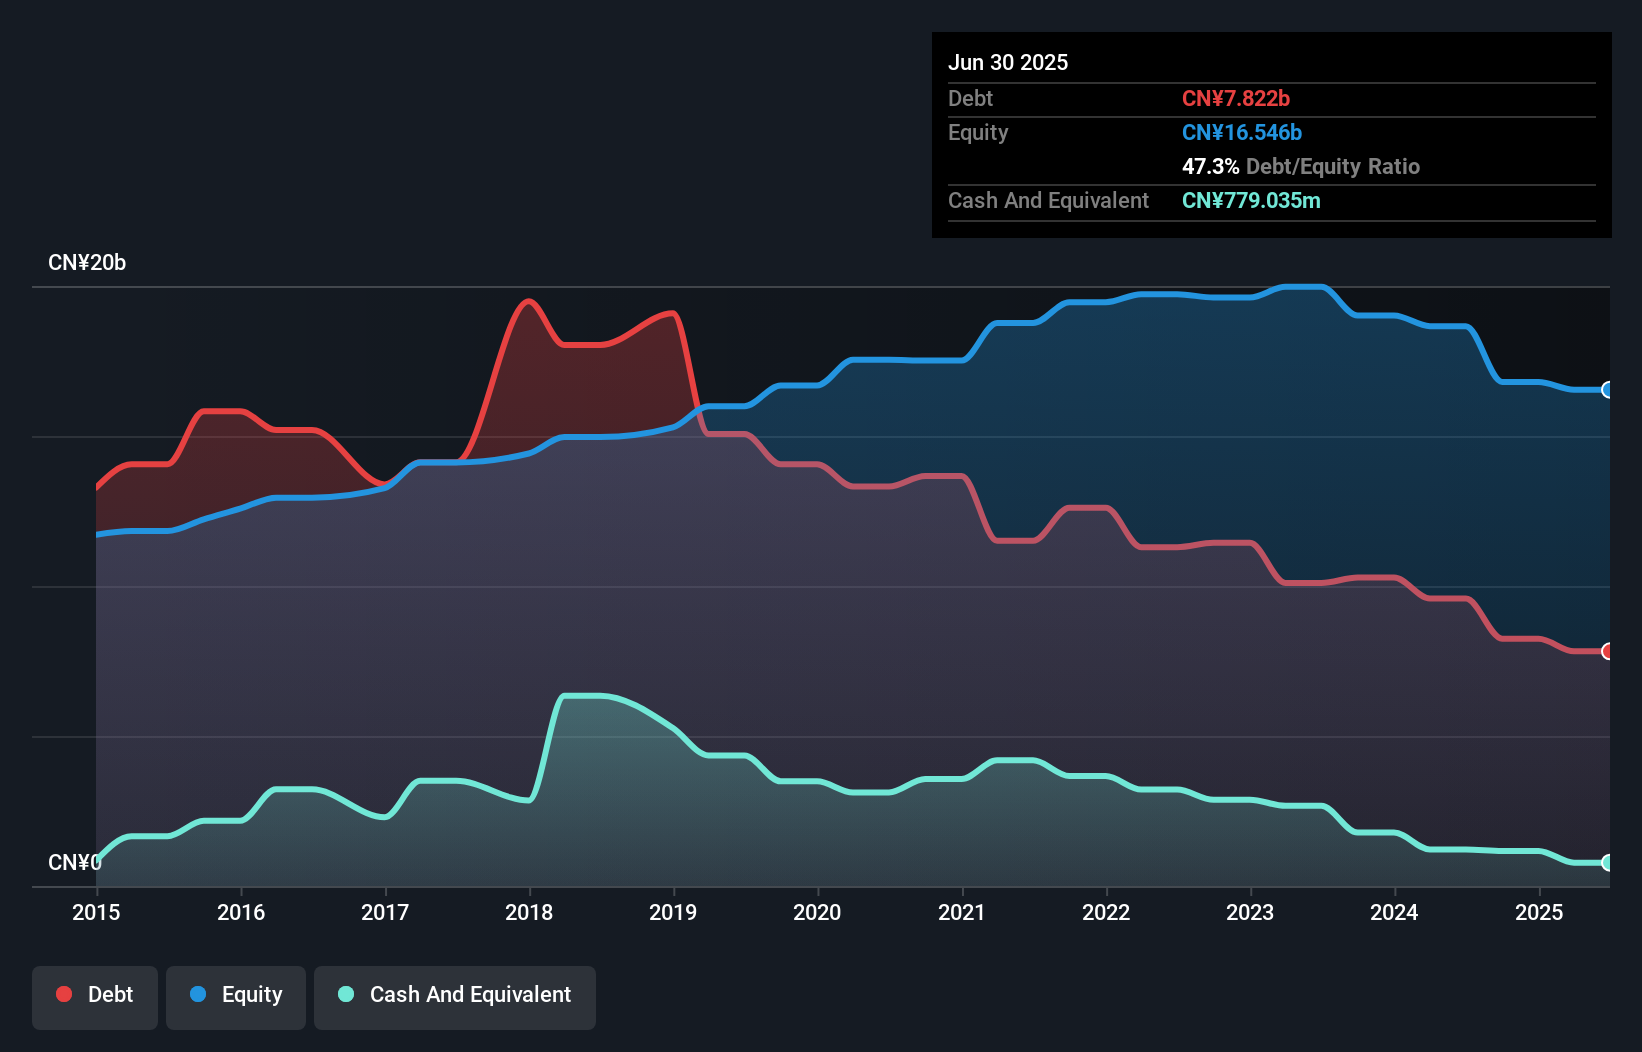
The image below, which you can click on for greater detail, shows that Mingfa Group (International) had debt of CN¥7.82b at the end of June 2025, a reduction from CN¥9.58b over a year. However, it also had CN¥779.0m in cash, and so its net debt is CN¥7.04b.
How Strong Is Mingfa Group (International)'s Balance Sheet?
Zooming in on the latest balance sheet data, we can see that Mingfa Group (International) had liabilities of CN¥38.1b due within 12 months and liabilities of CN¥5.05b due beyond that. Offsetting these obligations, it had cash of CN¥779.0m as well as receivables valued at CN¥5.68b due within 12 months. So it has liabilities totalling CN¥36.7b more than its cash and near-term receivables, combined.
This deficit casts a shadow over the CN¥891.9m company, like a colossus towering over mere mortals. So we'd watch its balance sheet closely, without a doubt. At the end of the day, Mingfa Group (International) would probably need a major re-capitalization if its creditors were to demand repayment. The balance sheet is clearly the area to focus on when you are analysing debt. But it is Mingfa Group (International)'s earnings that will influence how the balance sheet holds up in the future. So if you're keen to discover more about its earnings, it might be worth checking out this graph of its long term earnings trend.
Check out our latest analysis for Mingfa Group (International)
In the last year Mingfa Group (International) had a loss before interest and tax, and actually shrunk its revenue by 24%, to CN¥5.9b. That makes us nervous, to say the least.
Caveat Emptor
While Mingfa Group (International)'s falling revenue is about as heartwarming as a wet blanket, arguably its earnings before interest and tax (EBIT) loss is even less appealing. Indeed, it lost a very considerable CN¥278m at the EBIT level. Reflecting on this and the significant total liabilities, it's hard to know what to say about the stock because of our intense dis-affinity for it. Like every long-shot we're sure it has a glossy presentation outlining its blue-sky potential. But the reality is that it is low on liquid assets relative to liabilities, and it lost CN¥2.1b in the last year. So we think buying this stock is risky. When analysing debt levels, the balance sheet is the obvious place to start. But ultimately, every company can contain risks that exist outside of the balance sheet. Case in point: We've spotted 3 warning signs for Mingfa Group (International) you should be aware of, and 2 of them are significant.
If you're interested in investing in businesses that can grow profits without the burden of debt, then check out this free list of growing businesses that have net cash on the balance sheet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English