
Is Grand Field Group Holdings (HKG:115) Weighed On By Its Debt Load?
David Iben put it well when he said, 'Volatility is not a risk we care about. What we care about is avoiding the permanent loss of capital.' So it seems the smart money knows that debt - which is usually involved in bankruptcies - is a very important factor, when you assess how risky a company is. We can see that Grand Field Group Holdings Limited (HKG:115) does use debt in its business. But is this debt a concern to shareholders?
When Is Debt Dangerous?
Debt assists a business until the business has trouble paying it off, either with new capital or with free cash flow. If things get really bad, the lenders can take control of the business. However, a more frequent (but still costly) occurrence is where a company must issue shares at bargain-basement prices, permanently diluting shareholders, just to shore up its balance sheet. Of course, plenty of companies use debt to fund growth, without any negative consequences. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
How Much Debt Does Grand Field Group Holdings Carry?
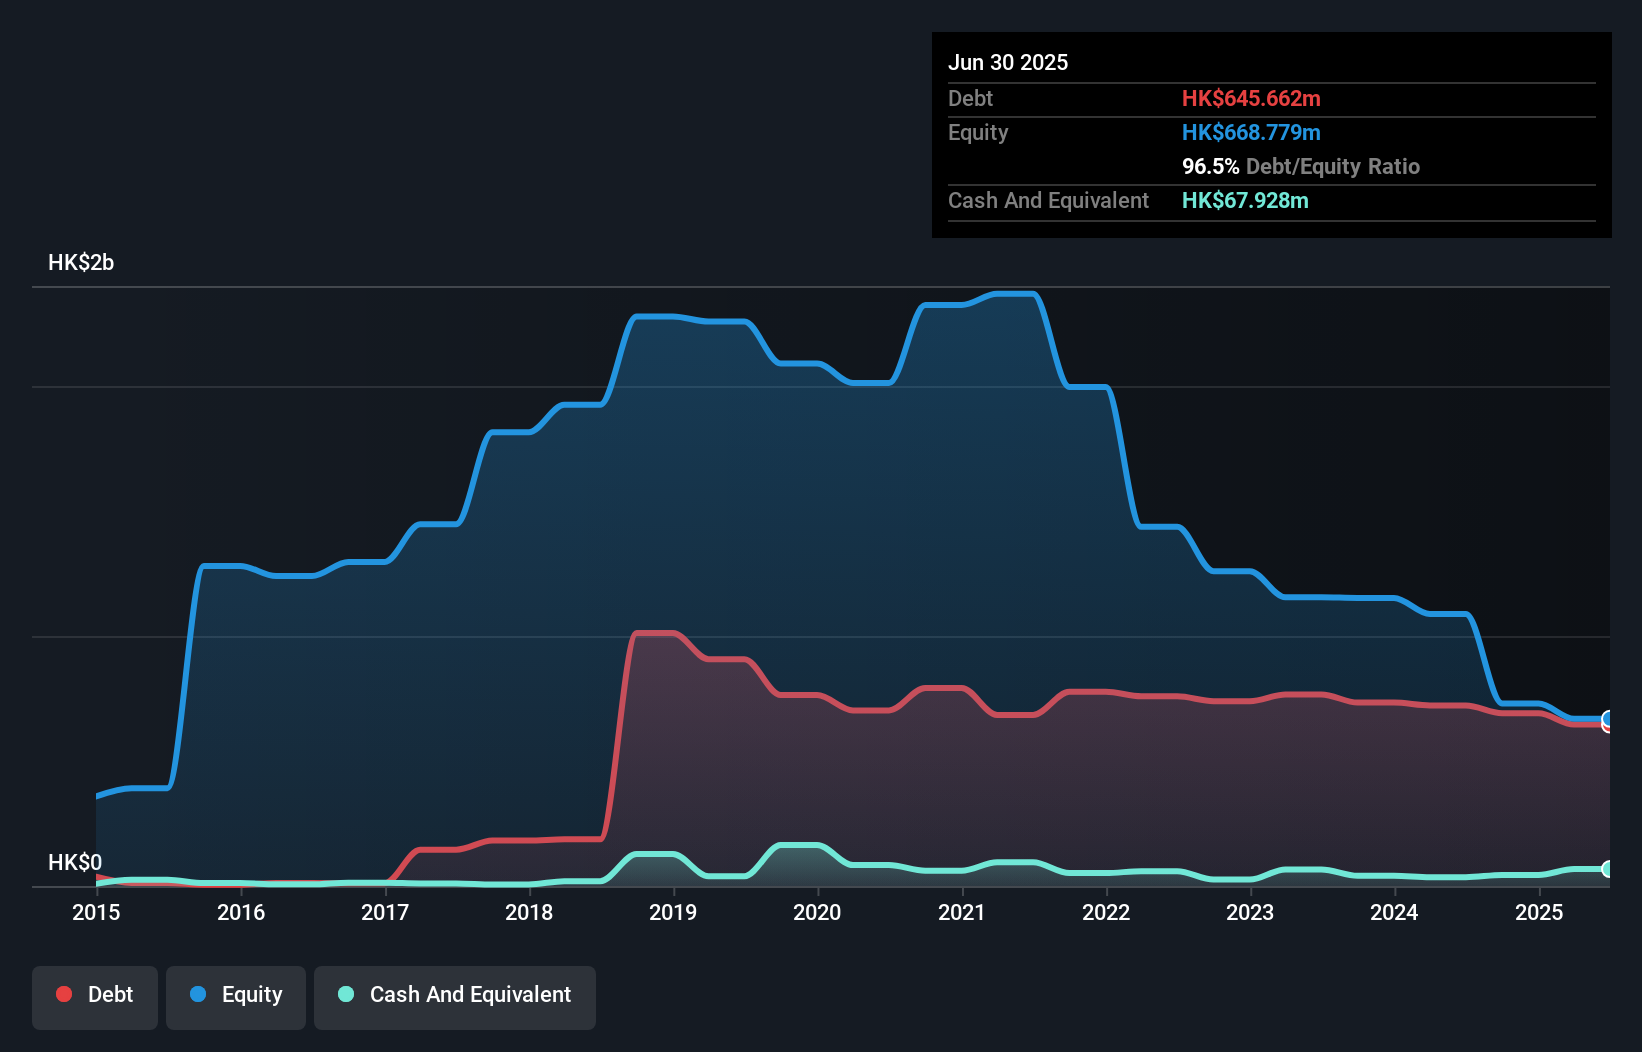
The image below, which you can click on for greater detail, shows that Grand Field Group Holdings had debt of HK$645.7m at the end of June 2025, a reduction from HK$722.1m over a year. However, it also had HK$67.9m in cash, and so its net debt is HK$577.7m.
How Strong Is Grand Field Group Holdings' Balance Sheet?
Zooming in on the latest balance sheet data, we can see that Grand Field Group Holdings had liabilities of HK$794.8m due within 12 months and liabilities of HK$476.0m due beyond that. On the other hand, it had cash of HK$67.9m and HK$47.1m worth of receivables due within a year. So its liabilities total HK$1.16b more than the combination of its cash and short-term receivables.
This deficit casts a shadow over the HK$78.7m company, like a colossus towering over mere mortals. So we definitely think shareholders need to watch this one closely. After all, Grand Field Group Holdings would likely require a major re-capitalisation if it had to pay its creditors today. When analysing debt levels, the balance sheet is the obvious place to start. But it is Grand Field Group Holdings's earnings that will influence how the balance sheet holds up in the future. So when considering debt, it's definitely worth looking at the earnings trend. Click here for an interactive snapshot.
See our latest analysis for Grand Field Group Holdings
In the last year Grand Field Group Holdings wasn't profitable at an EBIT level, but managed to grow its revenue by 18%, to HK$292m. That rate of growth is a bit slow for our taste, but it takes all types to make a world.
Caveat Emptor
Over the last twelve months Grand Field Group Holdings produced an earnings before interest and tax (EBIT) loss. Indeed, it lost a very considerable HK$162m at the EBIT level. When you combine this with the very significant balance sheet liabilities mentioned above, we are so wary of it that we are basically at a loss for the right words. Sure, the company might have a nice story about how they are going on to a brighter future. But the reality is that it is low on liquid assets relative to liabilities, and it lost HK$232m in the last year. So we think buying this stock is risky. When analysing debt levels, the balance sheet is the obvious place to start. But ultimately, every company can contain risks that exist outside of the balance sheet. For example, we've discovered 3 warning signs for Grand Field Group Holdings (2 don't sit too well with us!) that you should be aware of before investing here.
If you're interested in investing in businesses that can grow profits without the burden of debt, then check out this free list of growing businesses that have net cash on the balance sheet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English