
Is Sunshine Oilsands (HKG:2012) Weighed On By Its Debt Load?
Some say volatility, rather than debt, is the best way to think about risk as an investor, but Warren Buffett famously said that 'Volatility is far from synonymous with risk.' So it might be obvious that you need to consider debt, when you think about how risky any given stock is, because too much debt can sink a company. Importantly, Sunshine Oilsands Ltd. (HKG:2012) does carry debt. But should shareholders be worried about its use of debt?
When Is Debt A Problem?
Debt is a tool to help businesses grow, but if a business is incapable of paying off its lenders, then it exists at their mercy. In the worst case scenario, a company can go bankrupt if it cannot pay its creditors. However, a more usual (but still expensive) situation is where a company must dilute shareholders at a cheap share price simply to get debt under control. Of course, plenty of companies use debt to fund growth, without any negative consequences. The first thing to do when considering how much debt a business uses is to look at its cash and debt together.
What Is Sunshine Oilsands's Debt?
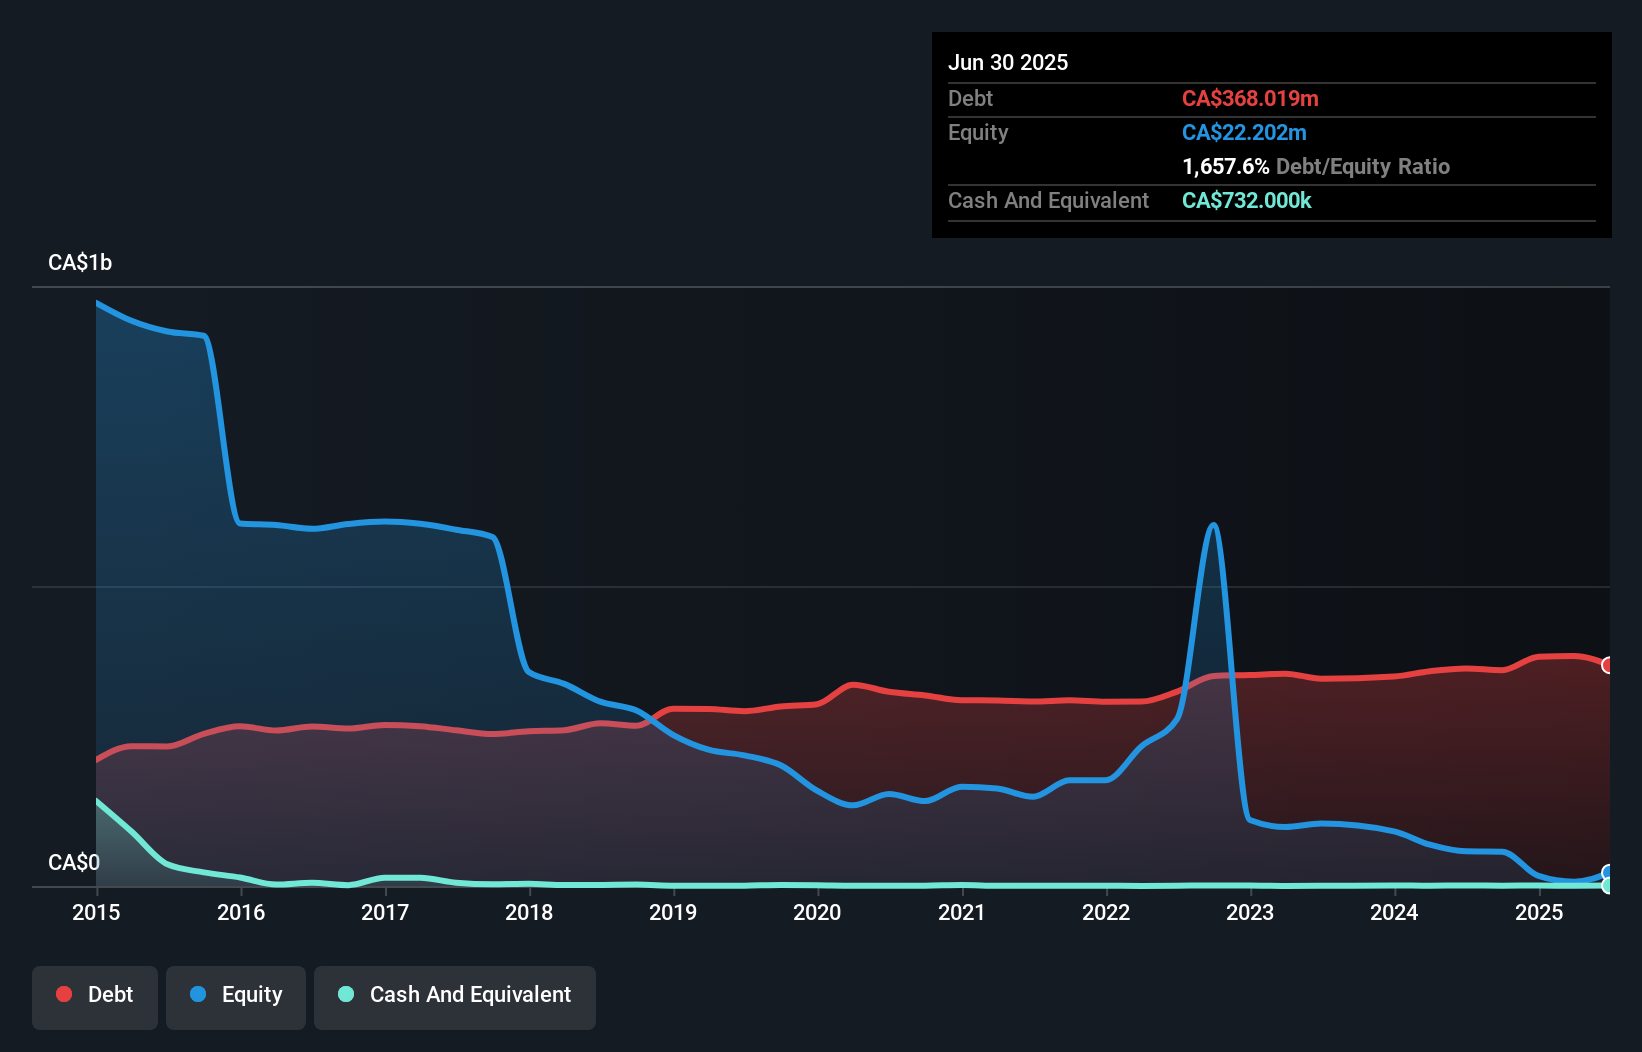
As you can see below, Sunshine Oilsands had CA$368.0m of debt, at June 2025, which is about the same as the year before. You can click the chart for greater detail. Net debt is about the same, since the it doesn't have much cash.
How Healthy Is Sunshine Oilsands' Balance Sheet?
Zooming in on the latest balance sheet data, we can see that Sunshine Oilsands had liabilities of CA$125.3m due within 12 months and liabilities of CA$594.7m due beyond that. Offsetting this, it had CA$732.0k in cash and CA$15.8m in receivables that were due within 12 months. So it has liabilities totalling CA$703.4m more than its cash and near-term receivables, combined.
The deficiency here weighs heavily on the CA$35.6m company itself, as if a child were struggling under the weight of an enormous back-pack full of books, his sports gear, and a trumpet. So we'd watch its balance sheet closely, without a doubt. After all, Sunshine Oilsands would likely require a major re-capitalisation if it had to pay its creditors today. There's no doubt that we learn most about debt from the balance sheet. But it is Sunshine Oilsands's earnings that will influence how the balance sheet holds up in the future. So if you're keen to discover more about its earnings, it might be worth checking out this graph of its long term earnings trend.
View our latest analysis for Sunshine Oilsands
In the last year Sunshine Oilsands had a loss before interest and tax, and actually shrunk its revenue by 79%, to CA$9.2m. That makes us nervous, to say the least.
Caveat Emptor
While Sunshine Oilsands's falling revenue is about as heartwarming as a wet blanket, arguably its earnings before interest and tax (EBIT) loss is even less appealing. Its EBIT loss was a whopping CA$23m. When you combine this with the very significant balance sheet liabilities mentioned above, we are so wary of it that we are basically at a loss for the right words. Like every long-shot we're sure it has a glossy presentation outlining its blue-sky potential. But the reality is that it is low on liquid assets relative to liabilities, and it burned through CA$4.6m in the last year. So is this a high risk stock? We think so, and we'd avoid it. When analysing debt levels, the balance sheet is the obvious place to start. But ultimately, every company can contain risks that exist outside of the balance sheet. To that end, you should learn about the 5 warning signs we've spotted with Sunshine Oilsands (including 3 which can't be ignored) .
If, after all that, you're more interested in a fast growing company with a rock-solid balance sheet, then check out our list of net cash growth stocks without delay.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English