
Exploring Baiwang And Two Other High Growth Tech Stocks In Asia
Amidst a backdrop of mixed global market performances and cautious sentiment around artificial intelligence spending, small-cap stocks have faced challenges, with the Russell 2000 Index experiencing a decline. In this environment, high growth tech companies in Asia present intriguing opportunities for investors seeking innovation-driven potential; understanding key factors such as scalability and adaptability is crucial when evaluating these stocks.
Top 10 High Growth Tech Companies In Asia
| Name | Revenue Growth | Earnings Growth | Growth Rating |
|---|---|---|---|
| Accton Technology | 21.66% | 24.66% | ★★★★★★ |
| Giant Network Group | 33.47% | 39.54% | ★★★★★★ |
| Suzhou TFC Optical Communication | 34.61% | 35.52% | ★★★★★★ |
| Shengyi TechnologyLtd | 21.50% | 32.87% | ★★★★★★ |
| Zhongji Innolight | 31.35% | 32.09% | ★★★★★★ |
| Fositek | 37.73% | 51.16% | ★★★★★★ |
| Shengyi Electronics | 24.67% | 33.32% | ★★★★★★ |
| Gold Circuit Electronics | 25.30% | 31.13% | ★★★★★★ |
| eWeLLLtd | 25.02% | 24.93% | ★★★★★★ |
| CARsgen Therapeutics Holdings | 100.40% | 118.16% | ★★★★★★ |
Let's uncover some gems from our specialized screener.
Baiwang (SEHK:6657)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Baiwang Co., Ltd. offers enterprise digitalization solutions via its Baiwang Cloud platform in China and has a market capitalization of approximately HK$4.01 billion.
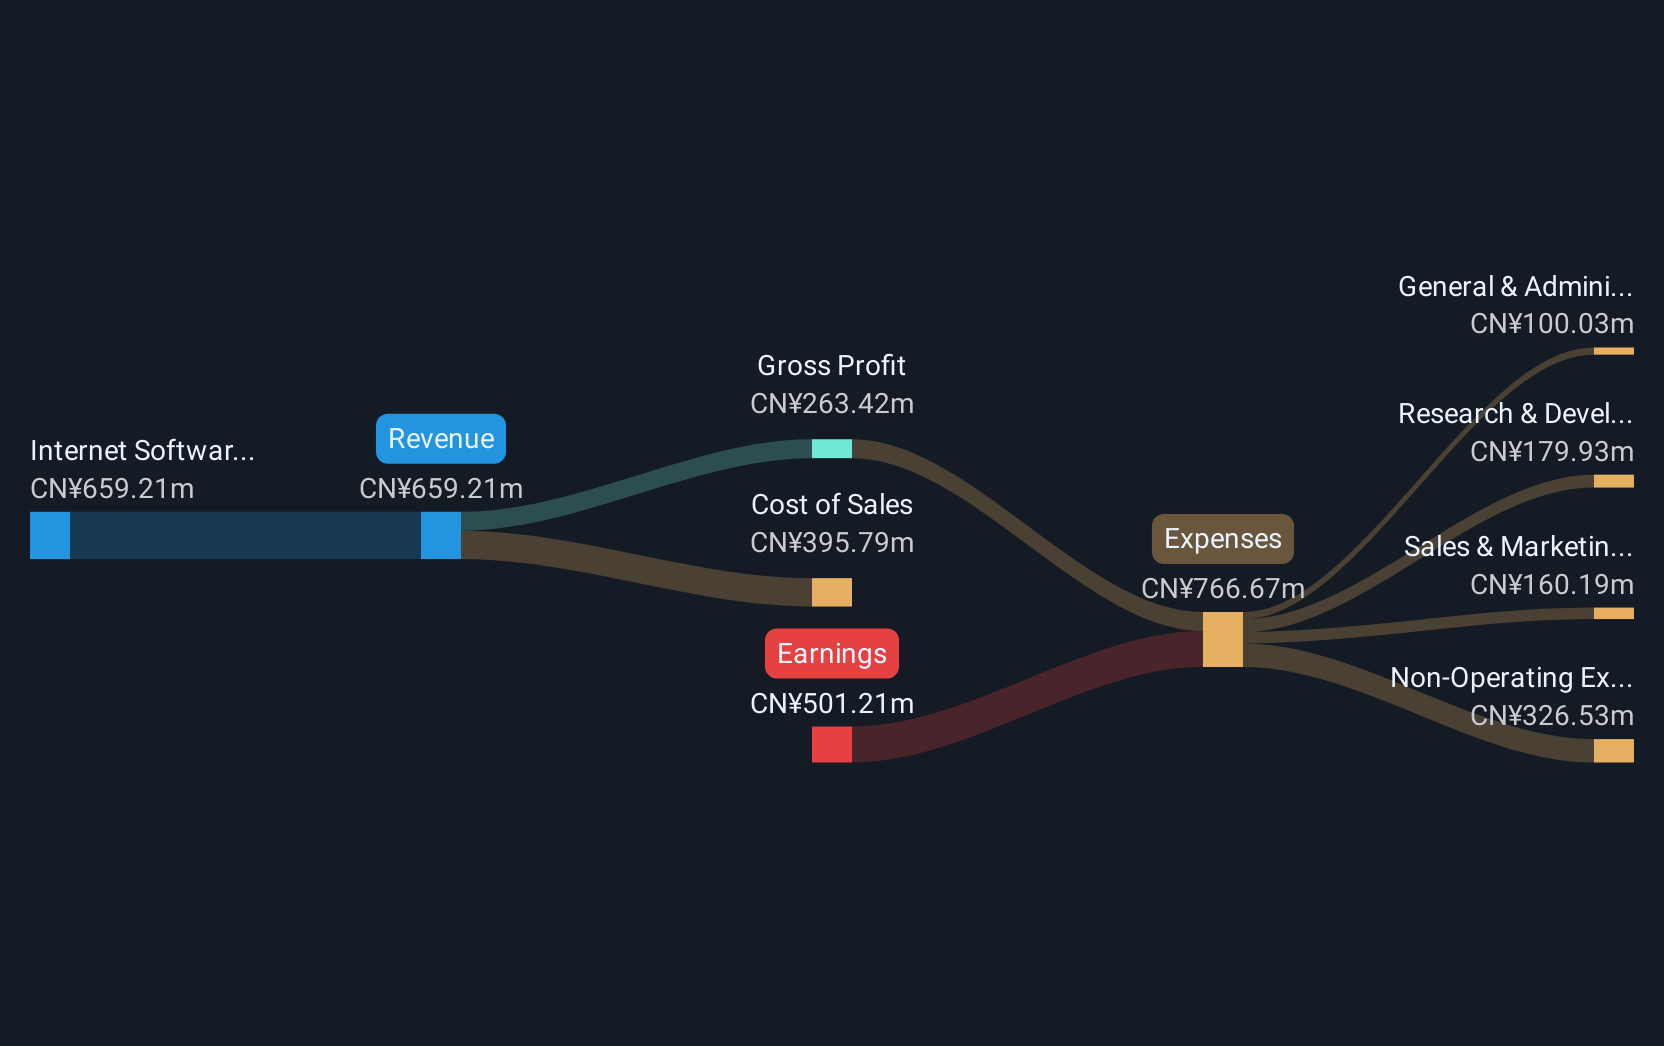
Operations: The company generates revenue primarily from its Internet Software & Services segment, which recorded CN¥725.25 million.
Baiwang Co., Ltd., with its recent pivot from a substantial net loss to a net income of CNY 3.72 million, showcases resilience and potential in the competitive tech landscape of Asia. This turnaround is underscored by a significant sales increase to CNY 347.59 million, up from CNY 281.55 million last year, reflecting an annualized revenue growth of 19%. Despite currently being unprofitable overall, Baiwang's earnings trajectory is promising with an expected explosive annual earnings growth rate of 106.6%. The company's commitment to innovation is evident from its R&D investments, aligning with forecasts predicting profitability within three years and positioning it favorably against the slower Hong Kong market growth rate of 8.5% per year.
- Get an in-depth perspective on Baiwang's performance by reading our health report here.
Evaluate Baiwang's historical performance by accessing our past performance report.
SVI (SET:SVI)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: SVI Public Company Limited, along with its subsidiaries, offers electronic manufacturing services across Asia and Europe, with a market capitalization of THB15.50 billion.
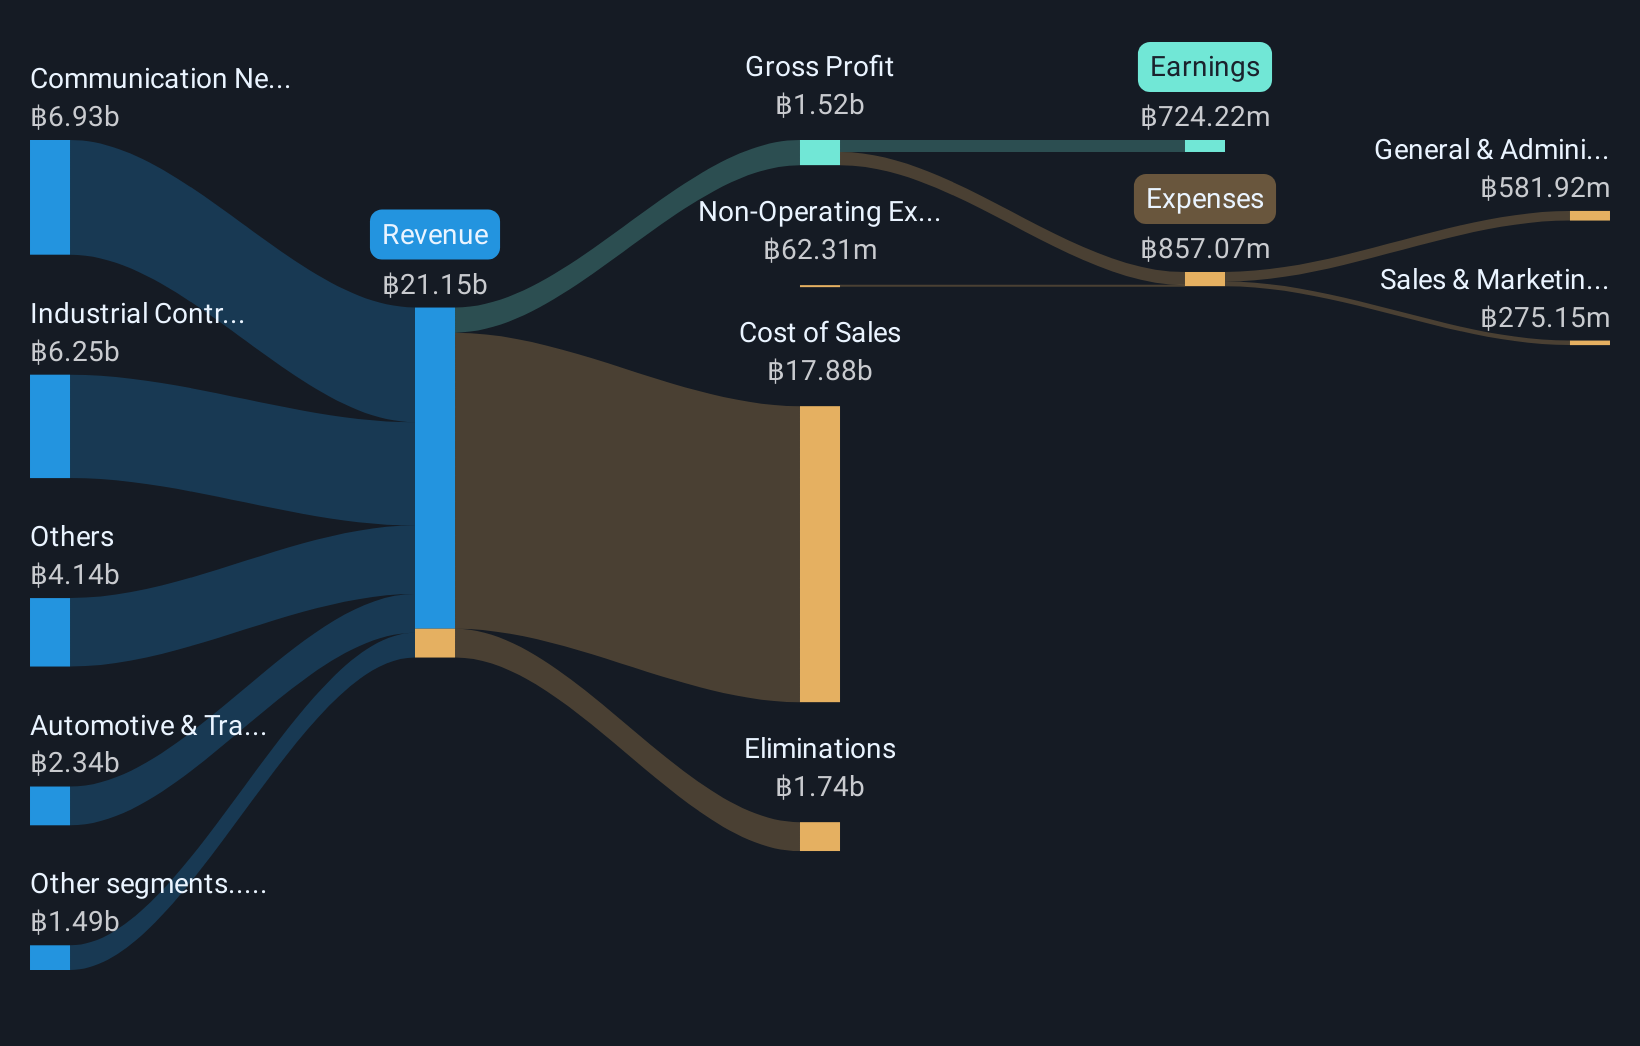
Operations: SVI Public Company Limited generates revenue primarily from its electronic manufacturing services, with key segments including Industrial Control System (THB6.78 billion) and Communication Network (THB6.48 billion). The company also serves the Automotive & Transportation and Professional Audio and Video sectors, contributing THB2.25 billion and THB1.47 billion respectively to its revenue streams.
SVI Public Company Limited, amidst a challenging year with sales dropping to THB 13.61 billion from THB 16.57 billion, managed to boost its net income significantly to THB 504.19 million, up from THB 1.06 billion previously reported. This resilience is highlighted by a robust earnings growth forecast of 21.4% annually, outpacing the Thai market's average of 12.8%. The company's strategic move towards delisting suggests a pivot in its business strategy possibly aimed at greater financial and operational flexibility amid recent acquisition activities where Pongsak Lothongkam aims to secure a full stake for THB 3.5 billion, indicating strong investor confidence and potential for future growth leveraging internal efficiencies and market position.
91APP (TPEX:6741)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: 91APP, Inc. is a Software-as-a-Service company offering retail software cloud and e-commerce value-added services across Taiwan, Hong Kong, and Malaysia with a market cap of NT$8.54 billion.
Operations: 91APP, Inc. generates revenue primarily through its retail software cloud services and e-commerce value-added offerings in Taiwan, Hong Kong, and Malaysia. The company focuses on leveraging its Software-as-a-Service model to provide scalable solutions for retailers in these regions.
91APP, a tech firm in Asia, demonstrates resilience with annualized revenue growth at 13.1% and earnings expansion by 20.4%. Despite a slight dip in net income from TWD 237.95 million to TWD 227.95 million over six months, the company maintains robust R&D investment, signaling ongoing innovation and competitive edge in the mobile commerce sector. This strategic focus on development is crucial as it aligns with shifting consumer behaviors towards digital solutions, positioning 91APP to capitalize on emerging market trends effectively.
- Dive into the specifics of 91APP here with our thorough health report.
Examine 91APP's past performance report to understand how it has performed in the past.

Summing It All Up
- Take a closer look at our Asian High Growth Tech and AI Stocks list of 190 companies by clicking here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English