
Returns On Capital At Minsheng Education Group (HKG:1569) Paint A Concerning Picture
To find a multi-bagger stock, what are the underlying trends we should look for in a business? Firstly, we'll want to see a proven return on capital employed (ROCE) that is increasing, and secondly, an expanding base of capital employed. Ultimately, this demonstrates that it's a business that is reinvesting profits at increasing rates of return. In light of that, when we looked at Minsheng Education Group (HKG:1569) and its ROCE trend, we weren't exactly thrilled.
Return On Capital Employed (ROCE): What Is It?
For those who don't know, ROCE is a measure of a company's yearly pre-tax profit (its return), relative to the capital employed in the business. To calculate this metric for Minsheng Education Group, this is the formula:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.0061 = CN¥48m ÷ (CN¥11b - CN¥2.8b) (Based on the trailing twelve months to June 2025).
Therefore, Minsheng Education Group has an ROCE of 0.6%. In absolute terms, that's a low return and it also under-performs the Consumer Services industry average of 10%.
View our latest analysis for Minsheng Education Group
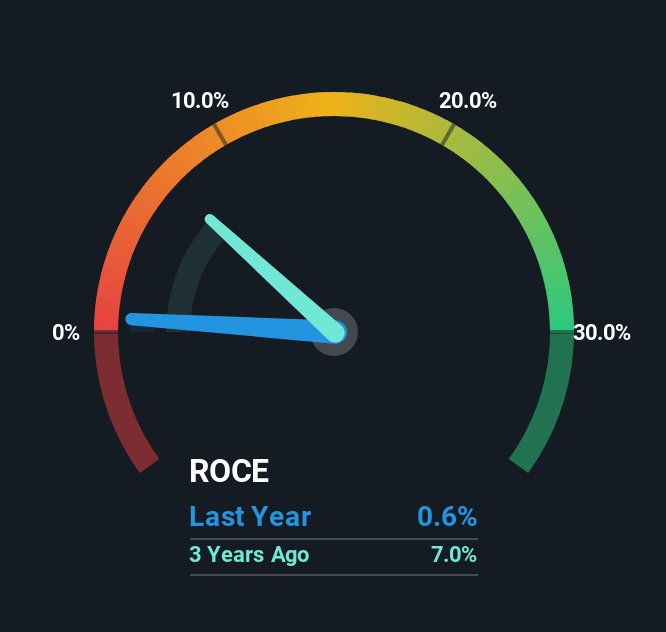
While the past is not representative of the future, it can be helpful to know how a company has performed historically, which is why we have this chart above. If you're interested in investigating Minsheng Education Group's past further, check out this free graph covering Minsheng Education Group's past earnings, revenue and cash flow.
What Can We Tell From Minsheng Education Group's ROCE Trend?
When we looked at the ROCE trend at Minsheng Education Group, we didn't gain much confidence. To be more specific, ROCE has fallen from 5.0% over the last five years. Given the business is employing more capital while revenue has slipped, this is a bit concerning. This could mean that the business is losing its competitive advantage or market share, because while more money is being put into ventures, it's actually producing a lower return - "less bang for their buck" per se.
The Bottom Line On Minsheng Education Group's ROCE
We're a bit apprehensive about Minsheng Education Group because despite more capital being deployed in the business, returns on that capital and sales have both fallen. Unsurprisingly then, the stock has dived 80% over the last five years, so investors are recognizing these changes and don't like the company's prospects. With underlying trends that aren't great in these areas, we'd consider looking elsewhere.
Minsheng Education Group does come with some risks though, we found 2 warning signs in our investment analysis, and 1 of those makes us a bit uncomfortable...
If you want to search for solid companies with great earnings, check out this free list of companies with good balance sheets and impressive returns on equity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English