
There's Been No Shortage Of Growth Recently For Inkeverse Group's (HKG:3700) Returns On Capital
What trends should we look for it we want to identify stocks that can multiply in value over the long term? In a perfect world, we'd like to see a company investing more capital into its business and ideally the returns earned from that capital are also increasing. Basically this means that a company has profitable initiatives that it can continue to reinvest in, which is a trait of a compounding machine. Speaking of which, we noticed some great changes in Inkeverse Group's (HKG:3700) returns on capital, so let's have a look.
Understanding Return On Capital Employed (ROCE)
Just to clarify if you're unsure, ROCE is a metric for evaluating how much pre-tax income (in percentage terms) a company earns on the capital invested in its business. To calculate this metric for Inkeverse Group, this is the formula:
Return on Capital Employed = Earnings Before Interest and Tax (EBIT) ÷ (Total Assets - Current Liabilities)
0.046 = CN¥218m ÷ (CN¥5.4b - CN¥654m) (Based on the trailing twelve months to June 2025).
So, Inkeverse Group has an ROCE of 4.6%. In absolute terms, that's a low return and it also under-performs the Interactive Media and Services industry average of 8.6%.
See our latest analysis for Inkeverse Group
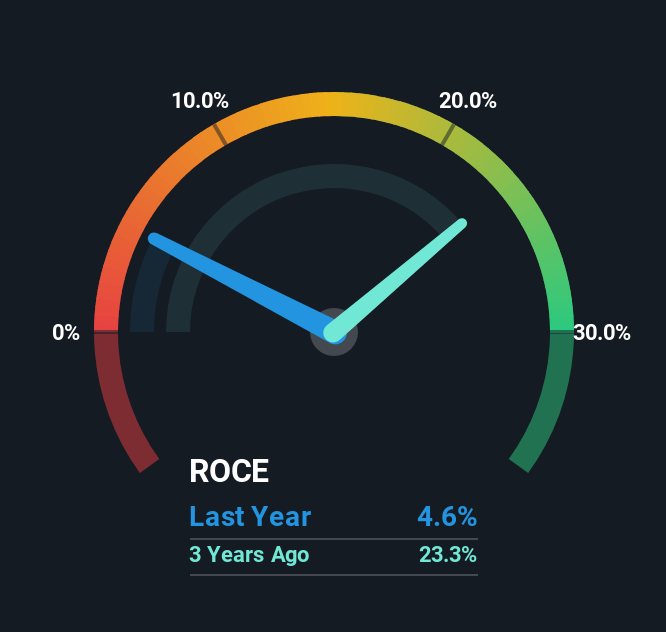
While the past is not representative of the future, it can be helpful to know how a company has performed historically, which is why we have this chart above. If you'd like to look at how Inkeverse Group has performed in the past in other metrics, you can view this free graph of Inkeverse Group's past earnings, revenue and cash flow.
What Can We Tell From Inkeverse Group's ROCE Trend?
Even though ROCE is still low in absolute terms, it's good to see it's heading in the right direction. Over the last five years, returns on capital employed have risen substantially to 4.6%. The amount of capital employed has increased too, by 31%. This can indicate that there's plenty of opportunities to invest capital internally and at ever higher rates, a combination that's common among multi-baggers.
Our Take On Inkeverse Group's ROCE
All in all, it's terrific to see that Inkeverse Group is reaping the rewards from prior investments and is growing its capital base. Astute investors may have an opportunity here because the stock has declined 56% in the last five years. That being the case, research into the company's current valuation metrics and future prospects seems fitting.
Inkeverse Group does have some risks though, and we've spotted 1 warning sign for Inkeverse Group that you might be interested in.
While Inkeverse Group isn't earning the highest return, check out this free list of companies that are earning high returns on equity with solid balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English