
Subdued Growth No Barrier To Edvance International Holdings Limited (HKG:1410) With Shares Advancing 47%
Edvance International Holdings Limited (HKG:1410) shares have continued their recent momentum with a 47% gain in the last month alone. The annual gain comes to 286% following the latest surge, making investors sit up and take notice.
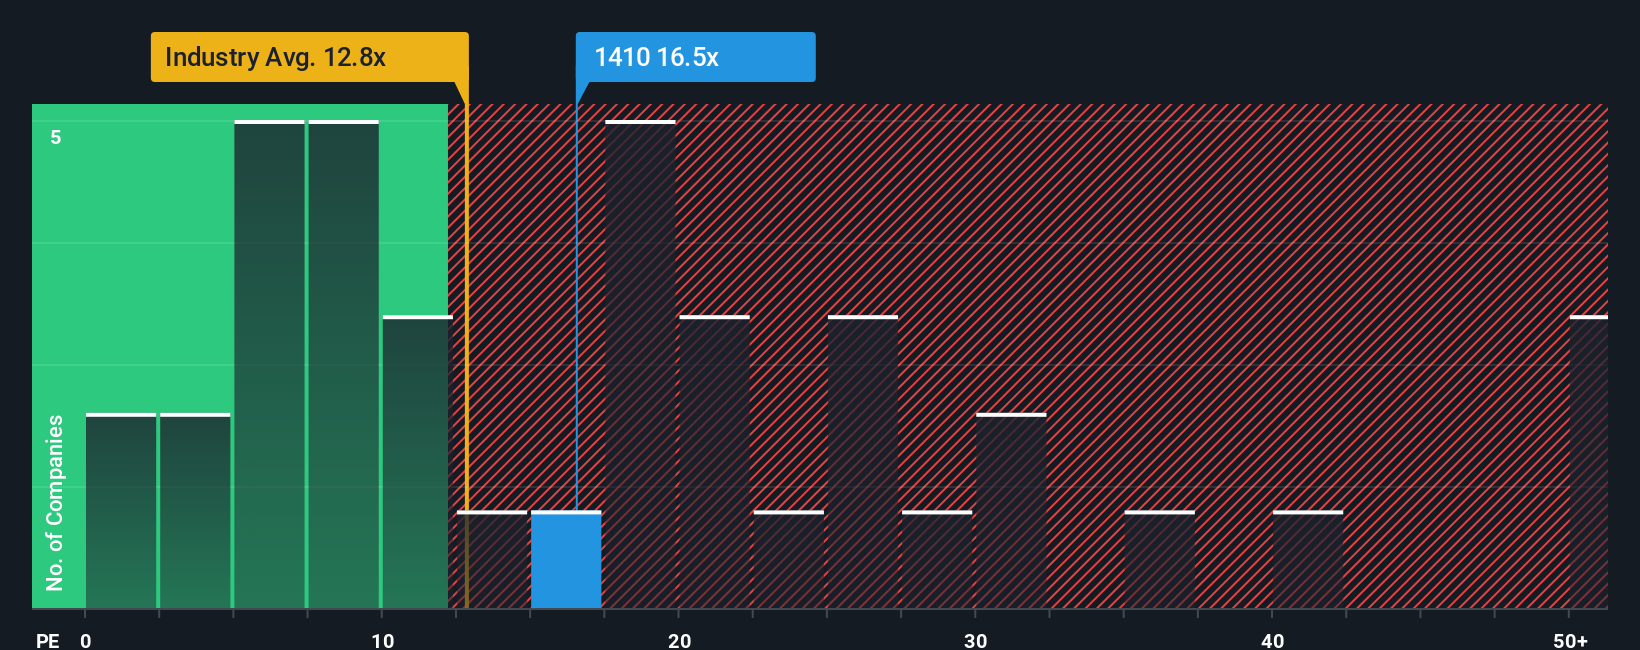
After such a large jump in price, given around half the companies in Hong Kong have price-to-earnings ratios (or "P/E's") below 12x, you may consider Edvance International Holdings as a stock to potentially avoid with its 16.5x P/E ratio. Nonetheless, we'd need to dig a little deeper to determine if there is a rational basis for the elevated P/E.
With earnings growth that's exceedingly strong of late, Edvance International Holdings has been doing very well. It seems that many are expecting the strong earnings performance to beat most other companies over the coming period, which has increased investors’ willingness to pay up for the stock. You'd really hope so, otherwise you're paying a pretty hefty price for no particular reason.
Check out our latest analysis for Edvance International Holdings
What Are Growth Metrics Telling Us About The High P/E?
There's an inherent assumption that a company should outperform the market for P/E ratios like Edvance International Holdings' to be considered reasonable.
If we review the last year of earnings growth, the company posted a terrific increase of 48%. Still, EPS has barely risen at all from three years ago in total, which is not ideal. Therefore, it's fair to say that earnings growth has been inconsistent recently for the company.
Comparing that to the market, which is predicted to deliver 20% growth in the next 12 months, the company's momentum is weaker based on recent medium-term annualised earnings results.
With this information, we find it concerning that Edvance International Holdings is trading at a P/E higher than the market. It seems most investors are ignoring the fairly limited recent growth rates and are hoping for a turnaround in the company's business prospects. There's a good chance existing shareholders are setting themselves up for future disappointment if the P/E falls to levels more in line with recent growth rates.
The Bottom Line On Edvance International Holdings' P/E
The large bounce in Edvance International Holdings' shares has lifted the company's P/E to a fairly high level. We'd say the price-to-earnings ratio's power isn't primarily as a valuation instrument but rather to gauge current investor sentiment and future expectations.
Our examination of Edvance International Holdings revealed its three-year earnings trends aren't impacting its high P/E anywhere near as much as we would have predicted, given they look worse than current market expectations. When we see weak earnings with slower than market growth, we suspect the share price is at risk of declining, sending the high P/E lower. Unless the recent medium-term conditions improve markedly, it's very challenging to accept these prices as being reasonable.
We don't want to rain on the parade too much, but we did also find 3 warning signs for Edvance International Holdings (2 are a bit concerning!) that you need to be mindful of.
If these risks are making you reconsider your opinion on Edvance International Holdings, explore our interactive list of high quality stocks to get an idea of what else is out there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English