
Why Investors Shouldn't Be Surprised By JW (Cayman) Therapeutics Co. Ltd's (HKG:2126) 25% Share Price Plunge
Unfortunately for some shareholders, the JW (Cayman) Therapeutics Co. Ltd (HKG:2126) share price has dived 25% in the last thirty days, prolonging recent pain. Looking back over the past twelve months the stock has been a solid performer regardless, with a gain of 11%.
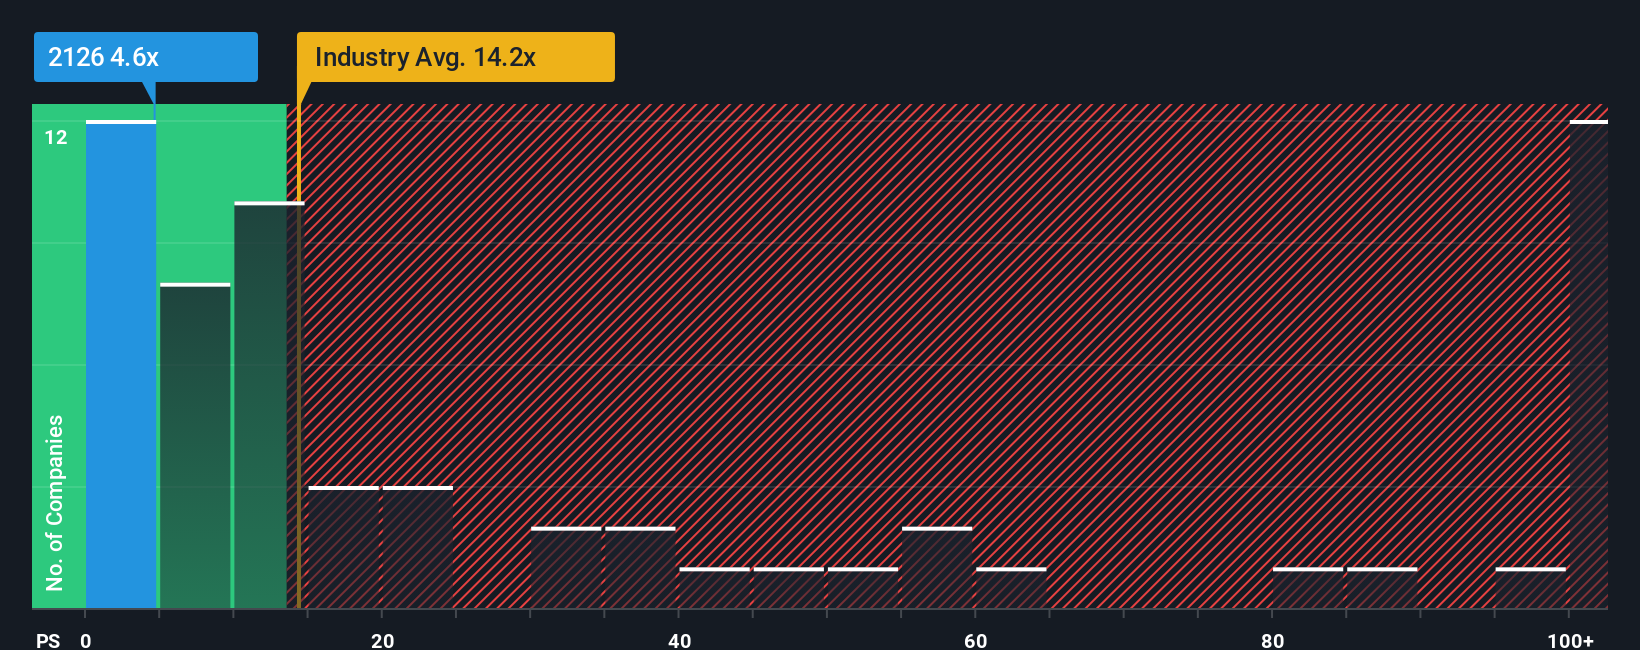
Since its price has dipped substantially, JW (Cayman) Therapeutics may look like a strong buying opportunity at present with its price-to-sales (or "P/S") ratio of 4.4x, considering almost half of all companies in the Biotechs industry in Hong Kong have P/S ratios greater than 14.2x and even P/S higher than 71x aren't out of the ordinary. Nonetheless, we'd need to dig a little deeper to determine if there is a rational basis for the highly reduced P/S.
View our latest analysis for JW (Cayman) Therapeutics
What Does JW (Cayman) Therapeutics' P/S Mean For Shareholders?
JW (Cayman) Therapeutics could be doing better as it's been growing revenue less than most other companies lately. Perhaps the market is expecting the current trend of poor revenue growth to continue, which has kept the P/S suppressed. If you still like the company, you'd be hoping revenue doesn't get any worse and that you could pick up some stock while it's out of favour.
Want the full picture on analyst estimates for the company? Then our free report on JW (Cayman) Therapeutics will help you uncover what's on the horizon.What Are Revenue Growth Metrics Telling Us About The Low P/S?
There's an inherent assumption that a company should far underperform the industry for P/S ratios like JW (Cayman) Therapeutics' to be considered reasonable.
If we review the last year of revenue growth, the company posted a worthy increase of 2.8%. The latest three year period has also seen an excellent 84% overall rise in revenue, aided somewhat by its short-term performance. Therefore, it's fair to say the revenue growth recently has been superb for the company.
Looking ahead now, revenue is anticipated to climb by 39% per annum during the coming three years according to the lone analyst following the company. Meanwhile, the rest of the industry is forecast to expand by 45% each year, which is noticeably more attractive.
With this information, we can see why JW (Cayman) Therapeutics is trading at a P/S lower than the industry. It seems most investors are expecting to see limited future growth and are only willing to pay a reduced amount for the stock.
The Key Takeaway
Having almost fallen off a cliff, JW (Cayman) Therapeutics' share price has pulled its P/S way down as well. While the price-to-sales ratio shouldn't be the defining factor in whether you buy a stock or not, it's quite a capable barometer of revenue expectations.
We've established that JW (Cayman) Therapeutics maintains its low P/S on the weakness of its forecast growth being lower than the wider industry, as expected. At this stage investors feel the potential for an improvement in revenue isn't great enough to justify a higher P/S ratio. The company will need a change of fortune to justify the P/S rising higher in the future.
It's always necessary to consider the ever-present spectre of investment risk. We've identified 1 warning sign with JW (Cayman) Therapeutics, and understanding should be part of your investment process.
It's important to make sure you look for a great company, not just the first idea you come across. So if growing profitability aligns with your idea of a great company, take a peek at this free list of interesting companies with strong recent earnings growth (and a low P/E).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English