
Assessing Dongfeng Motor Group (SEHK:489) Valuation After NEV Growth Offsets Weaker Legacy Sales
NEV growth offsets weaker legacy sales at Dongfeng Motor Group
Dongfeng Motor Group (SEHK:489) has drawn investor attention after reporting a 1.2% year-on-year rise in total sales volume for the first two months of 2026, driven by strong new energy vehicle performance.
NEV sales climbed 51.8% in this period, with commercial NEV volumes growing by 138.8%. This helped soften the impact of weaker traditional passenger vehicle sales at Dongfeng Nissan and Dongfeng Honda.
See our latest analysis for Dongfeng Motor Group.
At a share price of HK$9.66, Dongfeng Motor Group has logged a 7.81% 1 month share price return and a 9.52% year to date share price return. The 1 year total shareholder return of 115.62% and 3 year total shareholder return of almost 2x suggest that the recent NEV sales update comes on top of an already strong run, with near term momentum firming again after some short term volatility.
If this NEV story has you thinking about where else growth could come from, it may be worth scanning 29 robotics and automation stocks as another way to uncover automation focused opportunities across the market.
With Dongfeng Motor Group trading at HK$9.66 and sitting at a discount to both some valuation models and analyst targets after a strong run, the key question now is whether there is still a buying opportunity or if the market is already pricing in future growth.
Preferred Price-to-Sales Multiple of 0.6x: Is it justified?
At HK$9.66, Dongfeng Motor Group is described as trading at good value, with a P/S of 0.6x that sits below both its estimated fair level and the wider Asian auto group.
The P/S multiple compares the company’s market value to its revenue, which is useful when earnings are weak or volatile, as is the case here given Dongfeng Motor Group is currently loss making. With revenue of HK$120,968.87m and reported losses, the P/S lens lets you compare how much investors are paying for each dollar of sales without earnings distorting the picture.
Two reference points stand out. First, the company’s P/S of 0.6x is assessed as good value against an estimated fair P/S of 1.1x. This suggests the market price sits below a level the fair ratio model indicates it could move toward. Second, that same 0.6x is also described as good value against both peer averages and the broader Asian auto industry at 0.9x. This means the shares are priced at a discount on several benchmarks rather than just one model.
Explore the SWS fair ratio for Dongfeng Motor Group
Result: Preferred multiple of Price-to-Sales of 0.6x (UNDERVALUED)
However, you still need to keep an eye on Dongfeng Motor Group’s recent losses of CN¥1,312.07m, as well as any slowdown or policy shifts affecting NEV demand.
Find out about the key risks to this Dongfeng Motor Group narrative.
Another View: DCF points to a larger gap
Our DCF model indicates an even larger gap, with Dongfeng Motor Group at HK$9.66 compared with an estimated future cash flow value of HK$15.56, or about 38% below that figure. If both sales-based metrics and cash flow estimates point to value, how comfortable are you with the assumptions behind each?
Look into how the SWS DCF model arrives at its fair value.
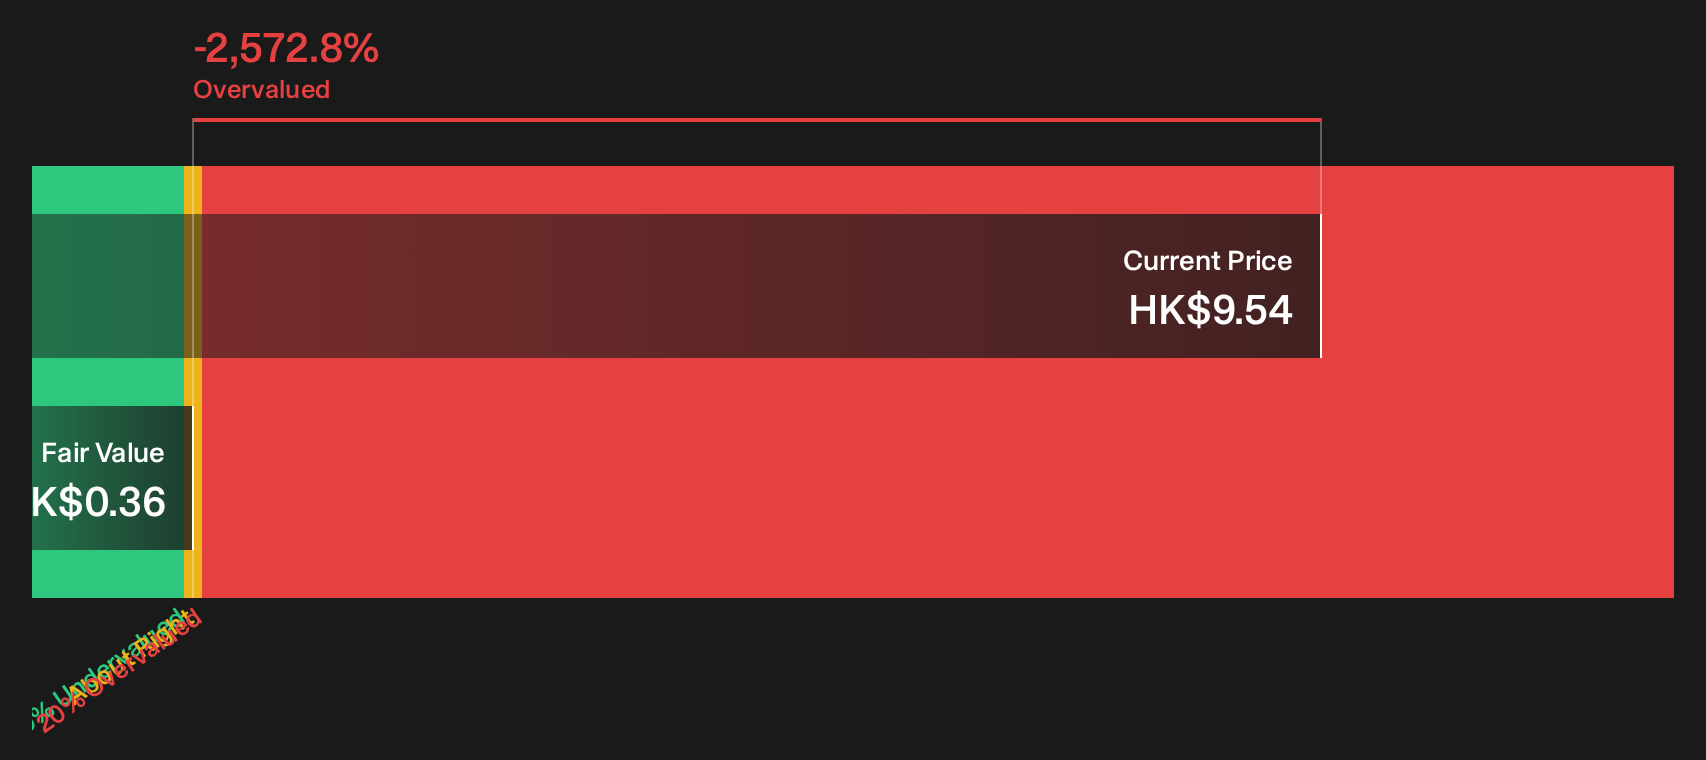
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dongfeng Motor Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 222 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of NEV momentum and valuation gaps leaves you unsure, take a moment to review the numbers yourself and move quickly while the data is fresh. To round out the picture and see what the market is excited about, look at the 3 key rewards.
Looking for more investment ideas?
If Dongfeng’s story has caught your attention, do not stop here. Broaden your watchlist while the market is still offering pockets of value.
- Zero in on quality at a discount by scanning our 222 high quality undervalued stocks to see which names currently line up with stronger fundamentals and cheaper P/S or P/E ratios.
- Build a steadier income stream by reviewing the 463 dividend fortresses, where yields from 5% and above come with an emphasis on resilience and payout consistency.
- Get ahead of the crowd by checking the screener containing 580 high quality undiscovered gems, which highlights companies with solid metrics that have yet to attract broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English