
We're Interested To See How Values Cultural Investment (HKG:1740) Uses Its Cash Hoard To Grow
We can readily understand why investors are attracted to unprofitable companies. For example, Values Cultural Investment (HKG:1740) shareholders have done very well over the last year, with the share price soaring by 206%. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
Given its strong share price performance, we think it's worthwhile for Values Cultural Investment shareholders to consider whether its cash burn is concerning. For the purpose of this article, we'll define cash burn as the amount of cash the company is spending each year to fund its growth (also called its negative free cash flow). First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
Does Values Cultural Investment Have A Long Cash Runway?
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In December 2025, Values Cultural Investment had CN¥20m in cash, and was debt-free. Importantly, its cash burn was CN¥1.7m over the trailing twelve months. That means it had a cash runway of very many years as of December 2025. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. The image below shows how its cash balance has been changing over the last few years.
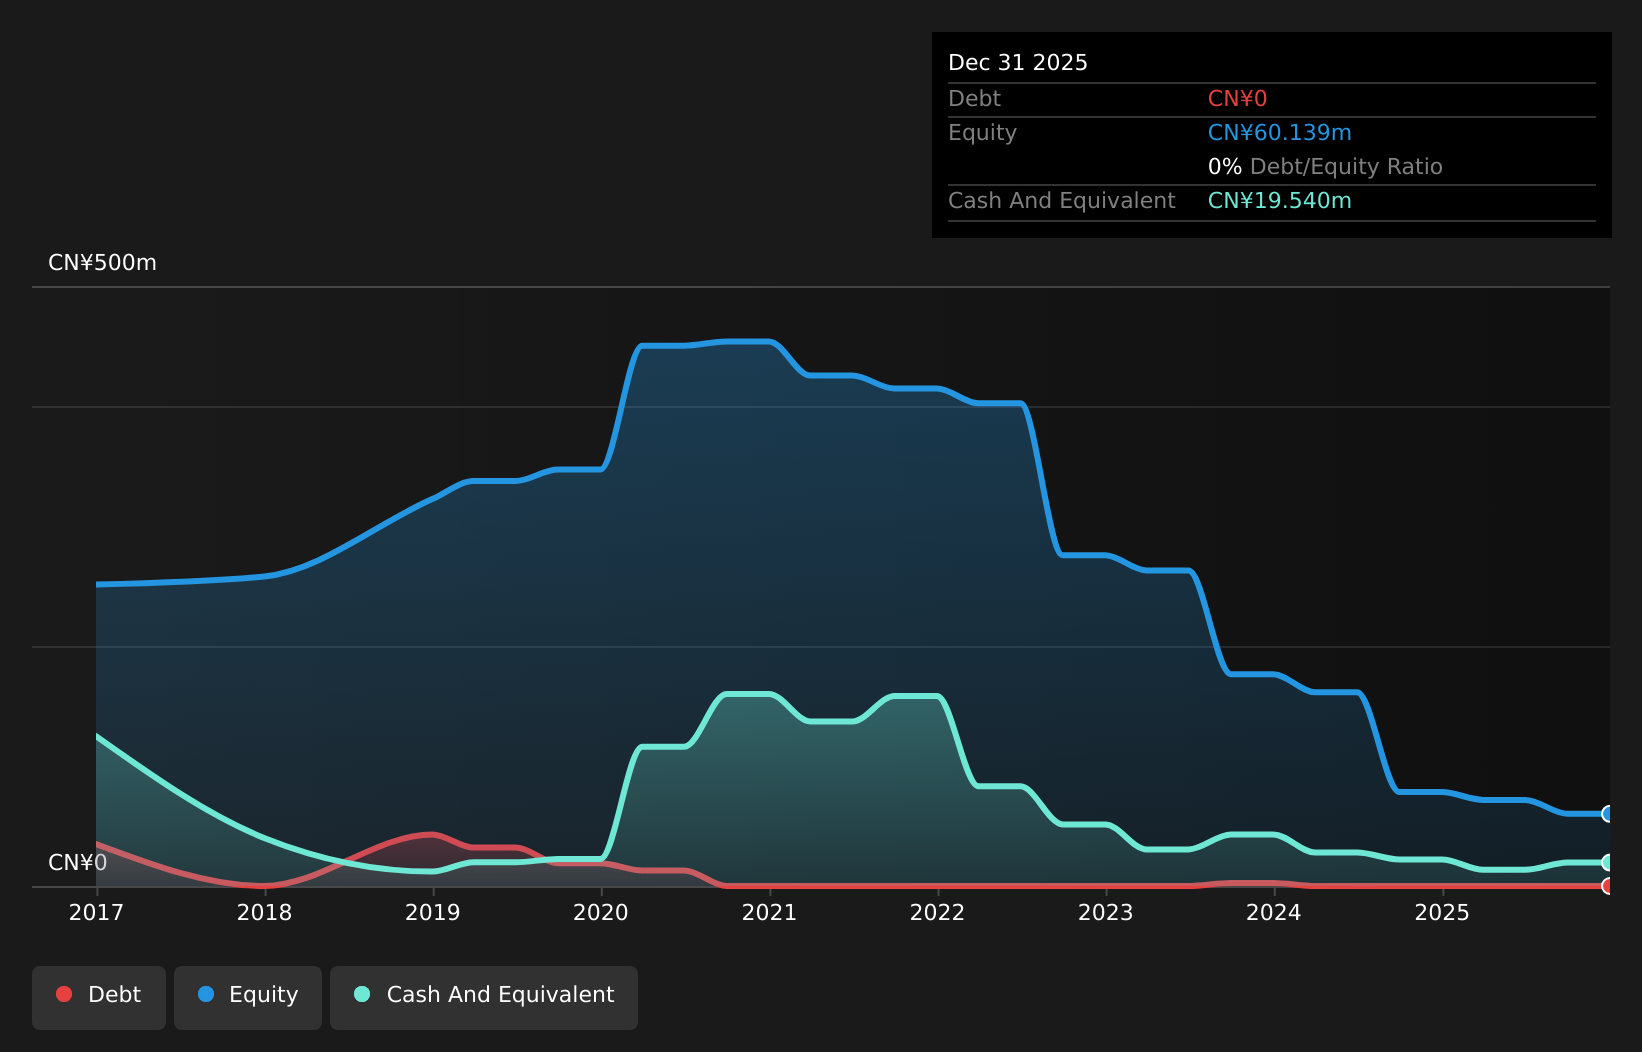
See our latest analysis for Values Cultural Investment
How Is Values Cultural Investment's Cash Burn Changing Over Time?
In our view, Values Cultural Investment doesn't yet produce significant amounts of operating revenue, since it reported just CN¥20m in the last twelve months. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. The good news, from a balance sheet perspective, is that it actually reduced its cash burn by 91% in the last twelve months. That might not be promising when it comes to business development, but it's good for the companies cash preservation. In reality, this article only makes a short study of the company's growth data. This graph of historic revenue growth shows how Values Cultural Investment is building its business over time.
Can Values Cultural Investment Raise More Cash Easily?
There's no doubt Values Cultural Investment's rapidly reducing cash burn brings comfort, but even if it's only hypothetical, it's always worth asking how easily it could raise more money to fund further growth. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Since it has a market capitalisation of CN¥176m, Values Cultural Investment's CN¥1.7m in cash burn equates to about 1.0% of its market value. That means it could easily issue a few shares to fund more growth, and might well be in a position to borrow cheaply.
So, Should We Worry About Values Cultural Investment's Cash Burn?
It may already be apparent to you that we're relatively comfortable with the way Values Cultural Investment is burning through its cash. In particular, we think its cash burn reduction stands out as evidence that the company is well on top of its spending. But it's fair to say that its cash burn relative to its market cap was also very reassuring. After taking into account the various metrics mentioned in this report, we're pretty comfortable with how the company is spending its cash. On another note, Values Cultural Investment has 4 warning signs (and 1 which is a bit concerning) we think you should know about.
Of course Values Cultural Investment may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English