
Park Systems And 2 Other High Growth Tech Stocks In Asia
As global markets navigate mixed signals, with U.S. indices showing varied performances and Asian markets experiencing a rotation from high-flying tech stocks to more traditional sectors, the spotlight is increasingly on high growth technology companies in Asia. In this dynamic environment, identifying strong stocks often involves looking for firms that demonstrate resilience through innovation and adaptability amidst shifting economic landscapes.
Top 10 High Growth Tech Companies In Asia
| Name | Revenue Growth | Earnings Growth | Growth Rating |
|---|---|---|---|
| Fositek | 29.08% | 37.44% | ★★★★★★ |
| Shengyi Electronics | 27.53% | 32.56% | ★★★★★★ |
| Zhongji Innolight | 44.00% | 48.86% | ★★★★★★ |
| Eoptolink Technology | 46.22% | 48.36% | ★★★★★★ |
| Gold Circuit Electronics | 36.81% | 38.20% | ★★★★★★ |
| Suzhou TFC Optical Communication | 40.69% | 39.36% | ★★★★★★ |
| King Slide Works | 31.47% | 28.24% | ★★★★★★ |
| Mobvista | 22.88% | 41.07% | ★★★★★★ |
| Unimicron Technology | 30.92% | 53.80% | ★★★★★★ |
| CARsgen Therapeutics Holdings | 63.94% | 80.57% | ★★★★★★ |
We're going to check out a few of the best picks from our screener tool.
Park Systems (KOSDAQ:A140860)
Simply Wall St Growth Rating: ★★★★★★
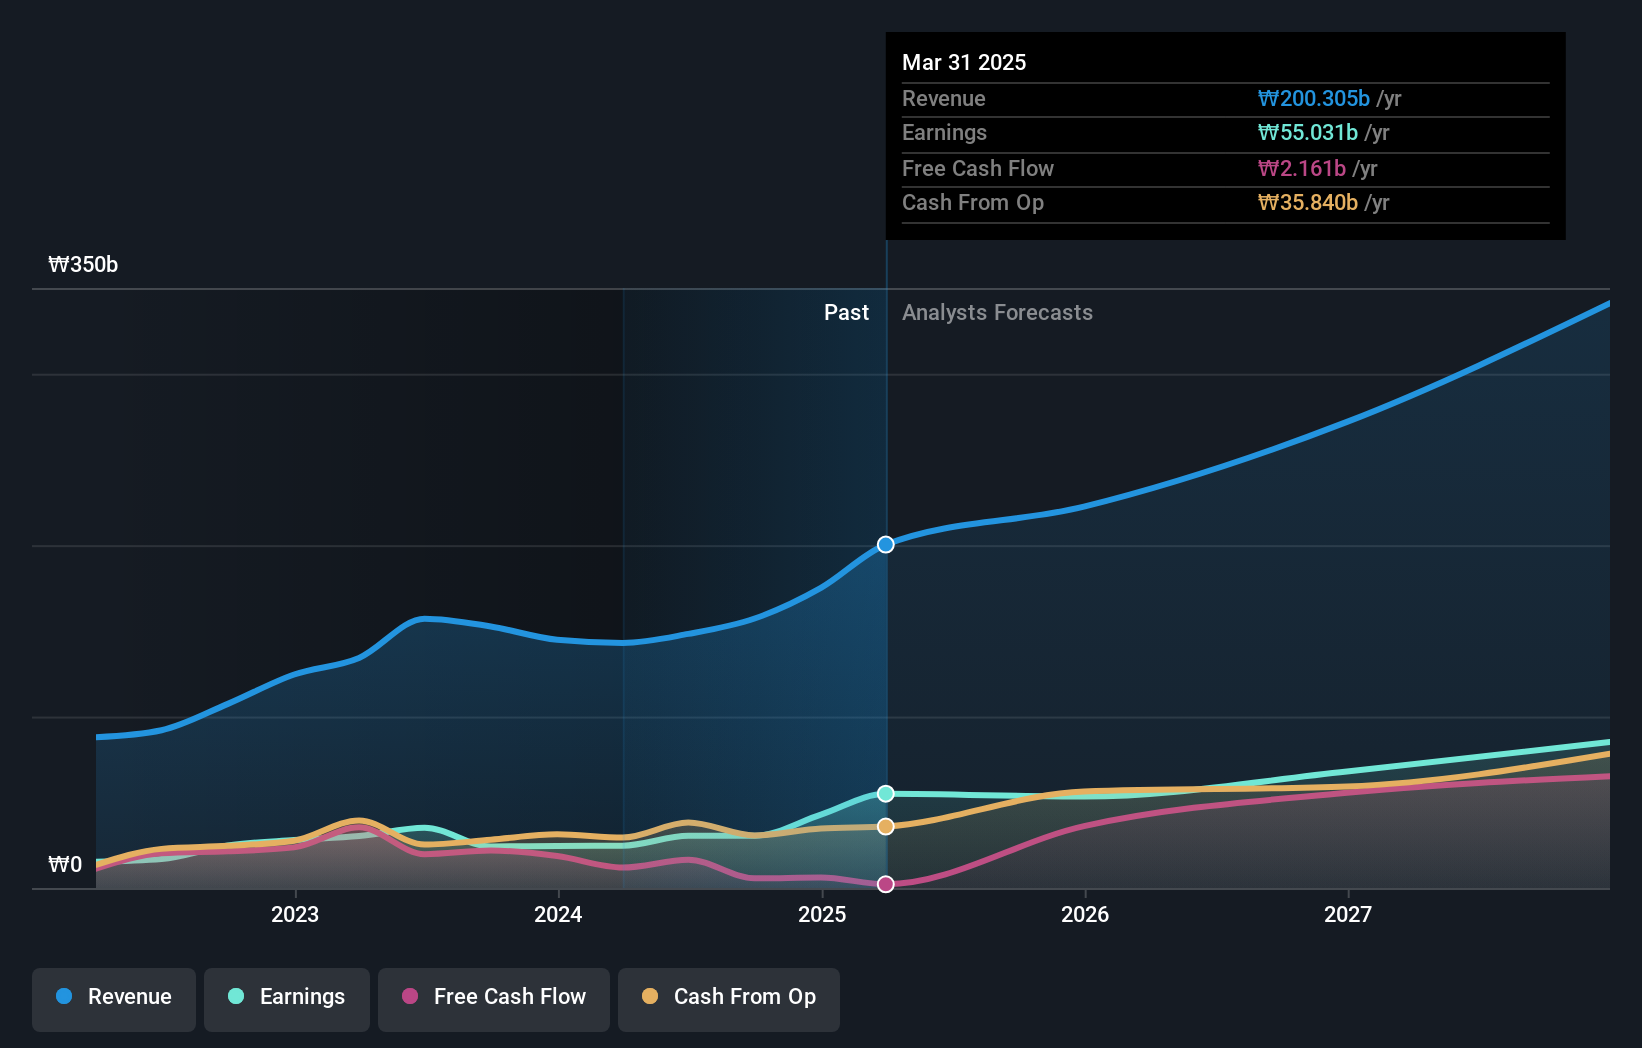
Overview: Park Systems Corp. is a company that develops, manufactures, and sells atomic force microscopy systems globally, with a market cap of ₩1.88 billion.
Operations: Park Systems Corp. generates revenue primarily from its Scientific & Technical Instruments segment, amounting to ₩194.07 billion. The company focuses on the global market for atomic force microscopy systems.
Park Systems Corp., a leader in atomic force microscopy, recently enhanced its technological portfolio with the launch of the Park FX40 IR, part of its Nano-IR spectrometer series. This innovation allows for nanoscale chemical analysis combined with surface topography acquisition, setting a new industry standard with sub-5 nm spatial resolution. Financially, Park Systems is poised for robust growth with expected annual revenue and earnings increases of 21.3% and 37%, respectively, outpacing the Korean market averages of 17.9% and 33.5%. However, it's worth noting that despite these advancements and growth forecasts, the company's profit margin has seen a decrease from last year’s 27.5% to 12.7%. This juxtaposition highlights both the potential rewards and risks associated with their aggressive expansion in high-tech instrumentation.
XD (SEHK:2400)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: XD Inc. is an investment holding company that focuses on developing, publishing, operating, and distributing mobile and web games both in Mainland China and internationally, with a market capitalization of approximately HK$23.37 billion.
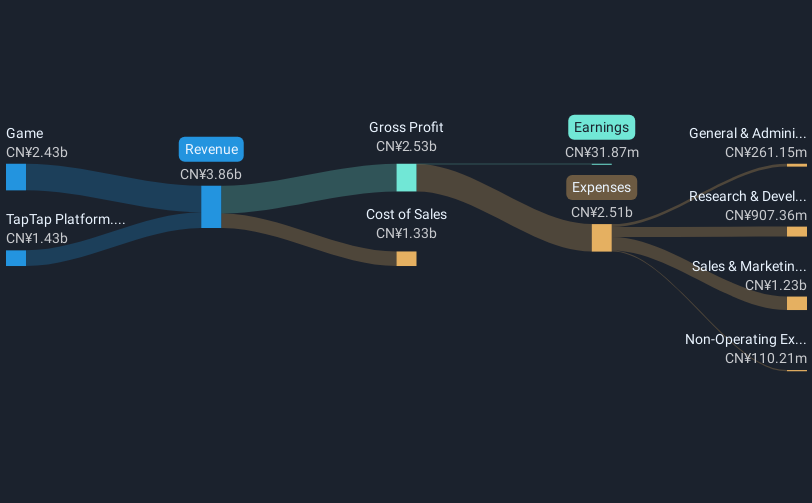
Operations: XD Inc. generates revenue primarily through its game development and distribution segment, which accounts for CN¥3.80 billion, and the TapTap platform, contributing CN¥1.97 billion. The company focuses on mobile and web games in both domestic and international markets.
XD Inc. stands out in the Asian tech landscape, not just for its robust revenue growth at 9.2% annually but also for its significant earnings acceleration, which has surged by 89.2% over the past year—outstripping the broader Entertainment industry's growth of 69.6%. This performance is underpinned by a strategic emphasis on R&D, where expenses have been meticulously managed to fuel innovation while still promoting financial health; indeed, R&D investments align closely with revenue gains and are integral to XD's competitive edge in rapidly evolving tech sectors. Additionally, the firm’s recent AGM highlighted governance steps poised to further solidify its market position, ensuring that XD remains agile in a dynamic economic environment. With earnings projected to climb by 13.3% annually, surpassing Hong Kong’s market average of 12.8%, XD is navigating its expansion with a clear focus on sustainable profitability and technological leadership.
- Dive into the specifics of XD here with our thorough health report.
Evaluate XD's historical performance by accessing our past performance report.
JST Group (SEHK:6687)
Simply Wall St Growth Rating: ★★★★★☆
Overview: JST Group Corporation Limited, along with its subsidiaries, offers e-commerce Software as a Service (SaaS) in China and has a market capitalization of approximately HK$6.08 billion.
Operations: JST Group generates revenue primarily through its Internet Software & Services segment, amounting to CN¥1.14 billion. The company focuses on providing e-commerce SaaS solutions in China.
JST Group, an emerging name in Asia's tech sector, is navigating a promising trajectory with its revenue growth forecast at 16.8% annually, outpacing the Hong Kong market average of 8.9%. This growth is underpinned by a strategic focus on R&D, where investments are closely aligned with revenue increases—vital for sustaining innovation and competitiveness. Recently initiating a share repurchase program underscores confidence in its financial strategy and future prospects. Moreover, the company's move towards profitability within three years alongside an expected earnings surge of 93% annually highlights its potential to reshape its market segment significantly.
- Unlock comprehensive insights into our analysis of JST Group stock in this health report.
Review our historical performance report to gain insights into JST Group's's past performance.

Summing It All Up
- Delve into our full catalog of 129 Asian High Growth Tech and AI Stocks here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English