Xiaomi (SEHK:1810), What Is Behind The Fresh Attention?
Xiaomi (SEHK:1810) is back in focus after Xiaomi Auto signed sales agreements with eight dealer groups in Germany, setting up a 2027 launch for its battery electric vehicles across Europe.
Despite the European EV push grabbing headlines, Xiaomi’s recent trading tells a more cautious story, with the share price down 34.6% year to date and the 1 year total shareholder return declining 52.2%. However, the 3 year total shareholder return is up 115.7%, and longer term momentum still reflects earlier gains.
Scan beyond Xiaomi and size up other potential beneficiaries of the EV and hardware trend with a curated list of 89 AI infrastructure stocks in one place.
The recent slump leaves Xiaomi trading well below earlier highs while the business expands into smartphones, IoT and EVs. Is this reset mainly about fundamentals, or a sharp swing in sentiment that valuation has not fully reconciled yet?
Most Popular Narrative: 36% Undervalued
Xiaomi’s most followed narrative pegs fair value at HK$41.16 against a last close of HK$26.36, implying a wide valuation gap that hinges on execution across EVs, AI and hardware.
Xiaomi is evolving into a vertically integrated “physical + digital” technology company, merging consumer electronics, mobility, and AI infrastructure under one ecosystem. The combination of EVs, AI models, robotics, and HyperOS integration gives the business multiple ways to scale revenue and improve profitability beyond its traditional smartphone base.
Want to see why this narrative supports such a large gap to the current HK$26.36 share price? The memo focuses on faster earnings, richer margins, and a premium multiple built around EV scale and high margin services. It also explores which segments carry most of the weight in that fair value calculation and how the forecast ties smartphones, IoT, internet services and cars into one model.
Result: Fair Value of HK$41.16 (UNDERVALUED)
Have a read of the narrative in full and understand what's behind the forecasts.
Still, the Xiaomi narrative can be knocked off course if smartphone profitability stays under pressure, or if heavy EV and AI spending fails to earn adequate returns.
Find out about the key risks to this Xiaomi narrative.
Another Look At Xiaomi’s Valuation
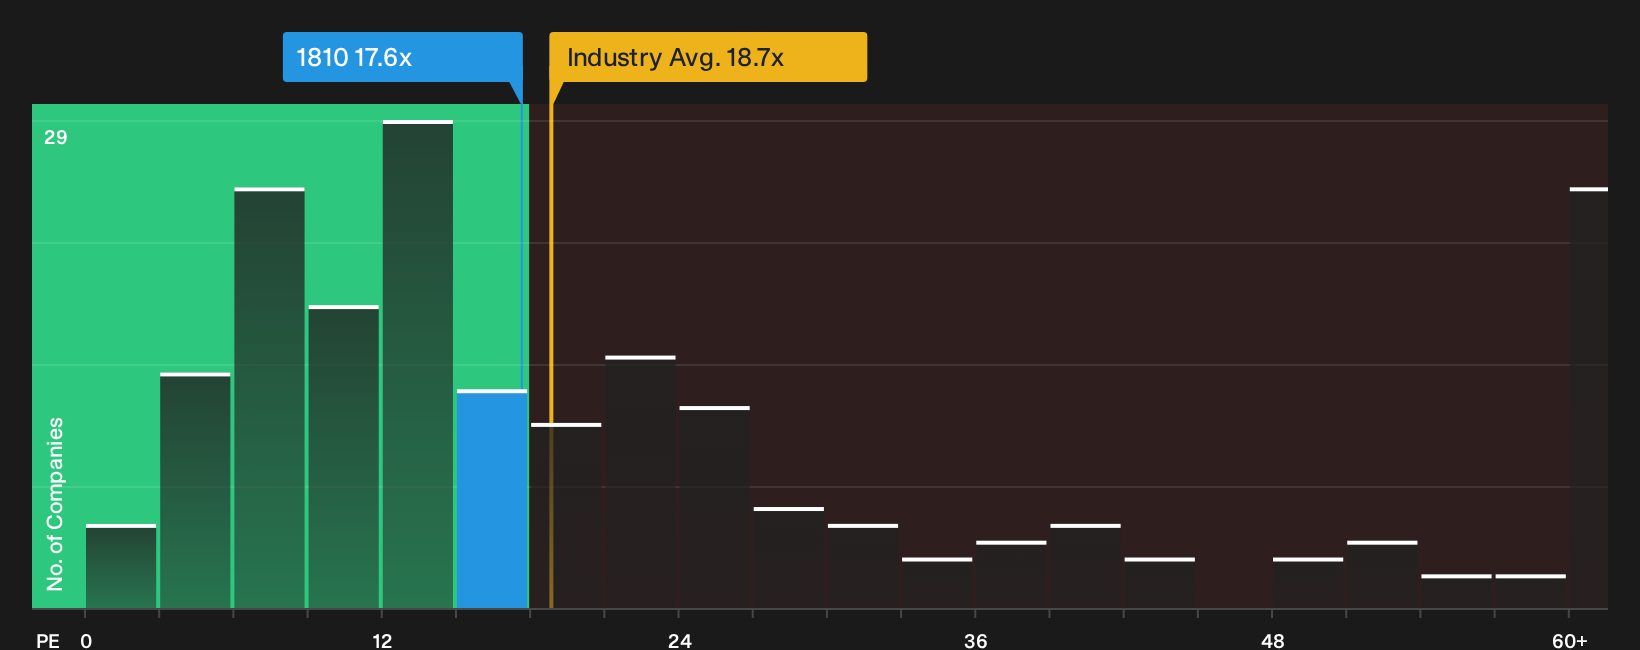
The first narrative points to a big discount, yet Xiaomi’s own numbers tell a more mixed story. The shares trade on a P/E of 17.6x, only slightly above the 17.1x fair ratio and just under the Asian tech average of 18.7x. Peers on 67.1x look far richer, which raises the question of whether this is a genuine mispricing or a reset toward a more grounded multiple.
See what the numbers say about this price in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Xiaomi is split, which creates a narrow window for you to weigh both sides of the data and decide where you land. To see how that balance of concerns and potential upsides stacks up in one place, review the 2 key rewards and 1 important warning sign.
Looking for more Xiaomi-sized ideas?
Do not stop at Xiaomi. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match your style before others move on them.
- Target steady compounding by focusing on companies with dependable payouts and resilient yield profiles through the 164 dividend fortresses.
- Hunt for mispriced quality by filtering for businesses that combine strong fundamentals with attractive valuations using the 182 high quality undervalued stocks.
- Prioritise resilience by zeroing in on companies with robust finances and durable fundamentals with the list of solid balance sheet and fundamentals (192 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English