
Silicon Motion (SIMO) Stock May Be Undervalued Despite Auto Cybersecurity Certification
Silicon Motion Technology has delivered an exceptional run over the past few years, so the key issue now is whether today’s share price still lines up with what its earnings can reasonably support. In that context, valuation has become less about the past chart and more about what the current earnings profile really justifies.
- Over the past 3 years the stock has returned about 4.7x, which puts real pressure on the question of whether earnings can carry that kind of re-rating.
- The new ISO/SAE 21434 automotive cybersecurity process certification may support expectations that Silicon Motion can win more automotive storage business, which matters for how durable and diversified its future profit stream could be.
- The analysts covering Silicon Motion Technology have run their own numbers. See what analysts think Silicon Motion Technology's shares could be worth.
The stock's next move may depend on whether the current price can be explained by what Silicon Motion earns today and what those earnings reasonably signal about the future.
If you want a broader watchlist of earnings driven stories alongside Silicon Motion Technology, a focused screen of 33 high quality undervalued stocks is a practical next stop for research.
Is Silicon Motion Technology Still Cheap on Earnings?
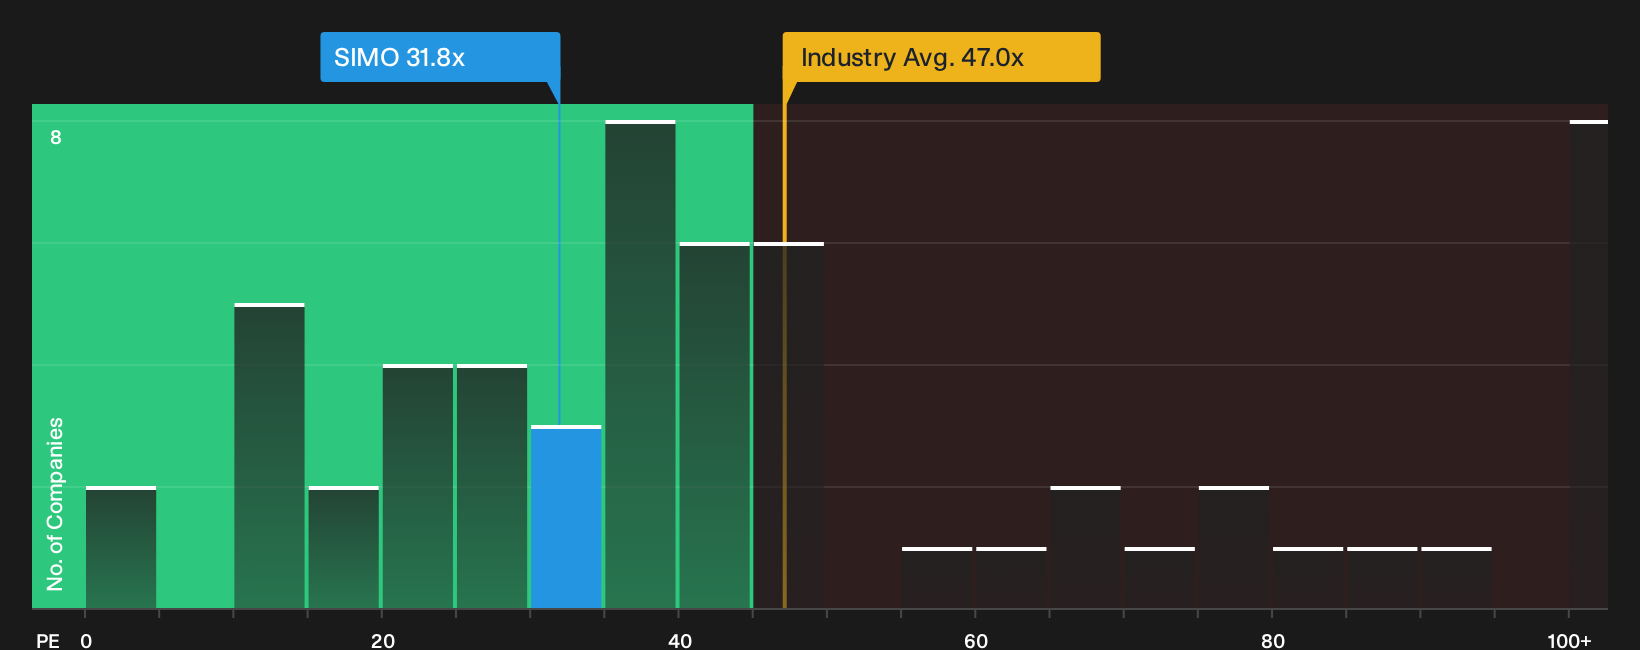
P/E works well for Silicon Motion Technology because the market is clearly keying off earnings for this kind of chip designer. The stock trades on a P/E of 31.8x, which is below both the semiconductor industry average of about 47.0x and a peer group closer to 47.9x. That gap indicates that investors are paying a lower price for each dollar of profit than they pay across much of the sector.
The valuation model suggests a tailored fair P/E that is higher than where Silicon Motion changes hands today, once factors like its growth profile, margins and risk mix are incorporated. Because the recent ISO/SAE 21434 certification supports the story around automotive storage and cybersecurity exposure, the current discount to that fair multiple suggests that the stock is not priced at the richer end of expectations. Explore the numbers behind Silicon Motion Technology's P/E valuation.
The Silicon Motion Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Silicon Motion Technology pick up where the valuation puzzle leaves off by explaining which combinations of future growth, profit margins and earnings power would need to hold for the stock to be worth materially more or less than it trades for today on the market. Each narrative anchors a fair value to a specific storyline about Silicon Motion Technology's potential catalysts and key risks, so you can track over time which version of events is actually unfolding on the Community page.
One of the top community narratives on Silicon Motion Technology: 26% undervalued
"Strategic partnerships with hyperscalers, automotive OEMs, and module makers, together with long-term supply agreements, are enhancing gross margin visibility…"
Discover why this Narrative puts Silicon Motion Technology at 26% undervalued.
Before acting on Silicon Motion Technology's valuation, there is one more factor to check
Price multiples only tell part of the story because the people setting Silicon Motion Technology's priorities, and the way their pay is structured, can heavily influence how those earnings evolve over time. See who runs Silicon Motion Technology and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English