
3 AI Infrastructure Stocks Facing Higher Rates and Bigger Chip Spending
AI is suddenly colliding with old fashioned interest rates, and the result is a market story that touches everything from data centers to utilities. With the Fed holding rates near 3.9% and 10 year yields around 5%, investors are being forced to rethink what they pay for future earnings just as AI related spending on chips and infrastructure ramps up. This piece breaks down three AI infrastructure enablers that appear especially exposed to these cross currents right now and explains how that mix of higher yields, structural inflation and massive tech capex could either help or hurt their long term appeal.
The stocks in this article are only a small sample of the AI infrastructure enablers that fit these filters, and the full screen surfaced 67 more established companies with equally compelling stories that are not covered here. To see the broader opportunity set, head straight into the AI Infrastructure Enablers (Data Centers, Chips, Power & Networking) screener to identify, filter, and analyze the AI infrastructure plays that best fit your own conviction and risk profile.
Onto Innovation (ONTO)
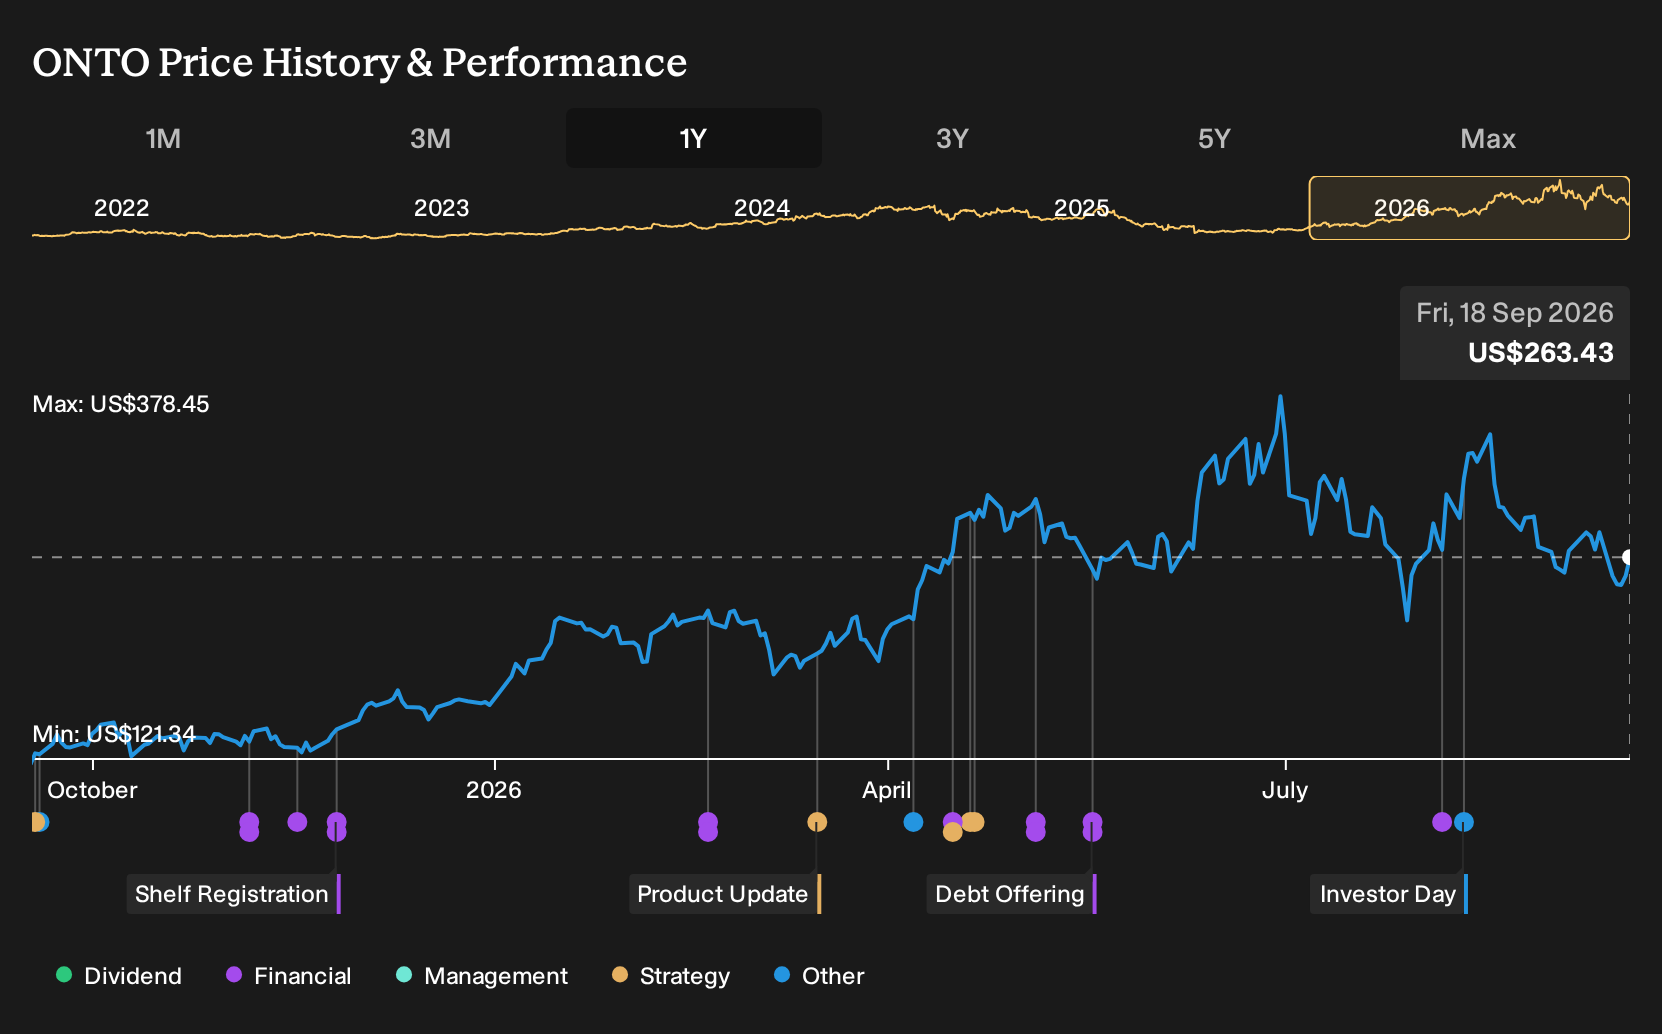
Onto Innovation sits right where the AI infrastructure build meets the messy reality of chip manufacturing, supplying inspection and metrology tools that help keep advanced AI processors and data center chips on track as complexity rises.
TSMC Production Ramp
Volume shipments for Dragonfly G5 systems are expected to begin during mid-2026, with revenue contributions potentially accelerating during the second half of the year.
What really matters for investors is how one less visible shift in packaging complexity ultimately flows through to pricing power and margins.
Onto Innovation designs and supports process control and metrology systems used across semiconductor manufacturing and advanced packaging, generating about US$1.1b from semiconductor equipment and services and carrying a roughly US$12.9b market cap.
That pricing power question is exactly what the full narrative for Onto Innovation unpacks, including how packaging complexity, capex cycles and risk could reshape Onto Innovation’s long range appeal.
KLA (KLAC)
KLA is one of the purest ways to get exposure to the hardware behind AI data centers, supplying inspection and metrology systems that help keep leading edge AI chips on yield and on schedule as factories push into more complex designs.
The advanced packaging market is experiencing early-stage, secular growth fueled by adoption of 2.5D/3D architectures and HBM, driving KLA's advanced packaging revenue target for 2025 up nearly 80% year-over-year with expectations that this trend is "closer to the beginning than the end" which directly expands KLA's addressable market and should provide multi-year upside to revenue.
The real swing factor is how one less visible shift in AI chip manufacturing intensity eventually feeds through to pricing, margins, and long term demand.
KLA Corporation supplies process control and inspection gear that underpins AI chip manufacturing, with most revenue from Semiconductor Process Control at about US$12.2b, smaller Specialty Semiconductor Process and PCB and Component Inspection lines near US$584m and US$750m, and a market value around US$231.2b.
That long term demand question is exactly what the full narrative for KLA tackles, separating hype from where KLA’s AI exposure could be accelerating or quietly stalling next.

Lam Research (LRCX)
Lam Research is one of the clearest AI infrastructure plays in the screener, because its etch and deposition tools are central to turning AI chip and memory capex into actual wafers on the ground.
Lam Research supplies wafer processing systems used to build AI and data center chips, with about US$23.2b in manufacturing and service revenue from semiconductor equipment and a roughly US$360.5b market value.
The June quarter's doubling is the first real evidence the upgrade cycle has started. If that spending stays front-loaded through calendar 2027 as management expects, FY2027 and FY2028 revenue estimates are too low.
What really moves the needle from here is how one quiet shift in memory and AI server demand shapes the durability of those margins and upgrade orders.
If that upgrade cycle really is just starting to bite, the full narrative for Lam Research outlines how Lam Research’s AI exposure, memory swings, and capex intensity could be quietly accelerating or stalling next.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Once momentum builds, breakout stories get caught on radars and ideal entry points start dropping away. Scan these curated lists while it still matters and act now.
- Target steady cash generators with strong balance sheets by running your filters through a curated list of solid balance sheet and fundamentals (23 results) while these businesses are still under heavier investor radars.
- Ride powerful macro trends by zeroing in on a hand picked 19 nuclear energy infrastructure stocks before capital flows change valuations and easy comparisons become less available.
- Position ahead of potential shifts in the metals space by combing through a focused 17 top copper producer stocks while these producers remain less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English