
Is Venture Global (VG) Stock Still Reasonable After Its 87% Rise?
Venture Global has been on a sharp year to date climb, yet the share price has pulled back in recent weeks, which puts fresh focus on whether the current valuation still lines up with what the business is earning. With the stock now trading at US$13.16, the key issue for you as an investor is whether that level can be explained by its underlying earnings power rather than recent momentum or broker headlines.
- The stock is up 86.9% year to date. Anyone buying today is effectively considering whether the company’s earnings can support a very different price profile than it had at the start of the year.
- Recent broker commentary around exported cargo volumes and adjusted EBITDA expectations signals that earnings forecasts and margin assumptions are moving targets. This can reshape how the market applies earnings based multiples to Venture Global.
- The analysts covering Venture Global have run their own numbers. See what analysts think Venture Global's shares could be worth.
The issue now is whether Venture Global’s current share price is justified by the earnings it is generating and what analysts expect it to produce next.
If you want to stress test this same earnings driven valuation question beyond Venture Global, run the rule over a wider set of companies using the 29 high quality undervalued stocks
Is Venture Global a Bargain on Earnings?
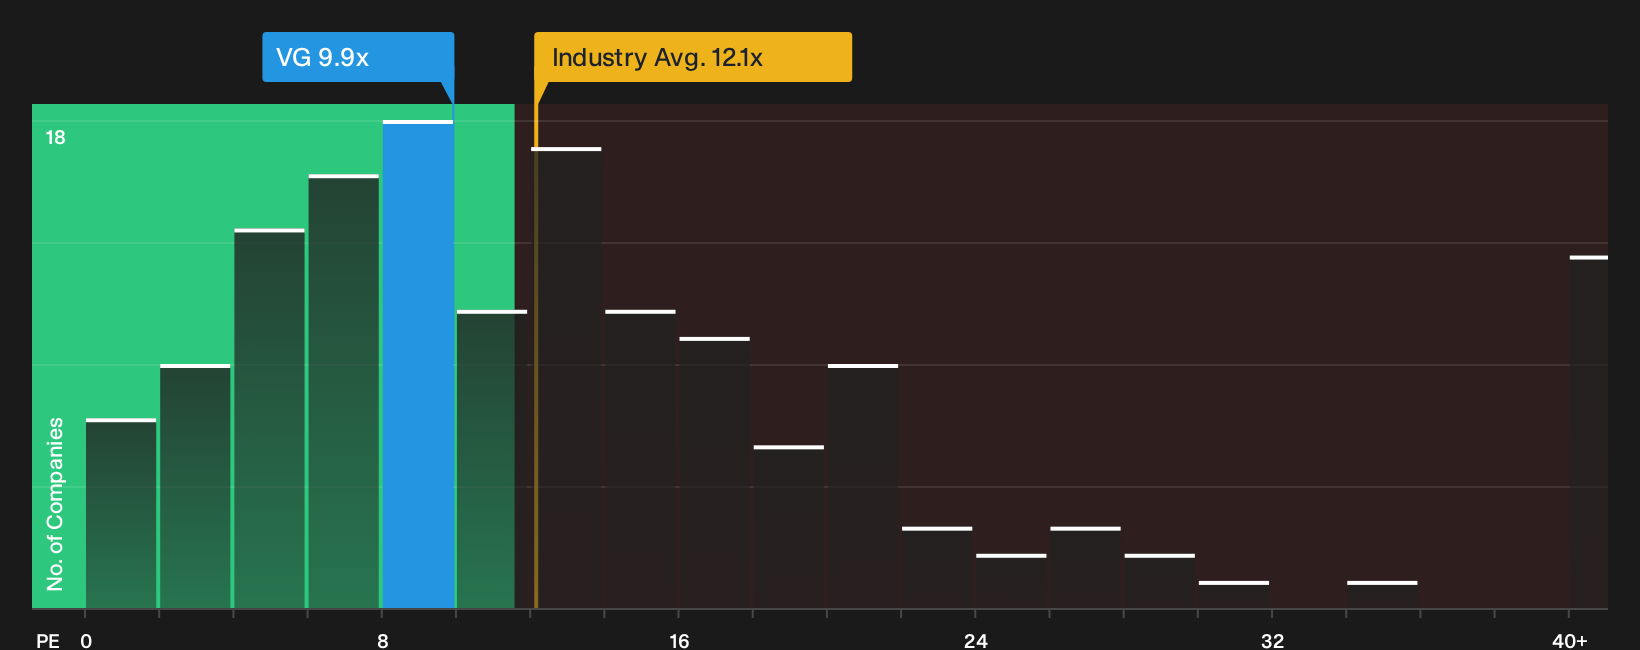
P/E fits Venture Global because the market is currently fixated on its reported net profit rather than cash flow. On that lens, the stock trades on roughly 9.9x earnings, which is below both the Oil and Gas sector average of about 12.1x and the wider peer group around 25.6x. The fair multiple implied by the valuation model is higher than where the shares trade, so the current P/E indicates the stock is undervalued on this framework.
Because recent broker updates have focused on adjusted EBITDA and cargo volumes, sentiment has been improving, yet the P/E still sits at a discount to sector and peer benchmarks. For you as an investor, that combination of more positive earnings commentary and a lower than modelled P/E suggests the market is not fully crediting Venture Global’s earning power on this metric. Explore the numbers behind Venture Global's P/E valuation.
The Venture Global Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Venture Global pick up where this valuation puzzle leaves off by spelling out what would need to happen to future growth, margins and earnings for the stock to be worth meaningfully more or less than today’s price on the Community page. Rather than focusing on a single P/E or valuation model output, each narrative lays out the specific assumptions behind its view of fair value so you can compare those inputs with actual results as they arrive.
One of the top community narratives on Venture Global: 6% undervalued
"This narrative explores a more pessimistic perspective on Venture Global compared to the consensus, based on a Fair Value that aligns with the bearish cohort..."
Discover why this Narrative puts Venture Global at 6% undervalued.
One more Venture Global check that belongs beside the price tag
Valuation only tells part of the story, because the people steering Venture Global and the way their pay is tied to results can heavily influence how that story plays out over time. See who runs Venture Global and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English