
Micron Technology (MU) Confirms Its Dividend, Is The Stock Fully Priced?
Micron Technology (MU) is back in focus after confirming its next cash dividend, with shares set to trade ex dividend on October 30 for a US$0.15 payout per share.
The dividend headline lands after a choppy stretch for Micron Technology, with the share price down 14.6% over the past week and 13.5% over 30 days. However, it is still showing a very strong year to date share price return of 178.6% and an exceptional 1 year total shareholder return of 334.8%, which indicates that momentum has cooled recently even though long term holders remain far ahead.
Scan how Micron Technology stacks up against other chip players by zeroing in on 55 AI infrastructure stocks, which is powering the same AI and data center trends driving attention to this dividend update.
The pullback in Micron Technology after such a steep 1 year run can signal either a reset in expectations or a real rethink of the business. The valuation work starts at that point.
Most Popular Narrative: 56% Undervalued
The most followed narrative on Micron Technology pegs fair value at about $2,018 per share, compared with the recent $878.84 close, which points to a wide gap the market has yet to close according to Pure_Research.
"The primary engine driving Micron''s forward revenue growth is the industry-wide transition to vertically stacked HBM4 architectures. The high physical complexity of HBM manufacturing introduces a steep 3x physical wafer consumption penalty over standard planar DDR5. This wafer penalty reduces the global supply of standard commodity memory, creating a persistent supply deficit. This structural tightness allows memory manufacturers to transition away from annual fixed-price agreements toward compressed monthly contracts featuring retroactive, spot-linked post-settlement clauses, maximizing capital returns."
See why 132 investors see Micron Technology as 56% undervalued.
Result: Fair Value of $2,018.05 (UNDERVALUED)
Still, Micron Technology’s heavy capital spending commitments and reliance on a concentrated group of hyperscale customers could quickly challenge that undervalued narrative if conditions shift.
Find out about the key risks to this Micron Technology narrative.
Another View On Micron Technology’s Value
A plain discounted cash flow lens tells a different story to Pure_Research’s narrative. Our model pegs Micron Technology’s value near $850.74 per share, slightly below the recent $878.84 price, which frames the stock as a touch expensive rather than deeply discounted. Which valuation scaffolding do you trust more?
For readers who want to see how this cash flow view is built line by line, the next step is to unpack the SWS DCF model in detail, including its key assumptions and sensitivities Look into how the SWS DCF model arrives at its fair value.
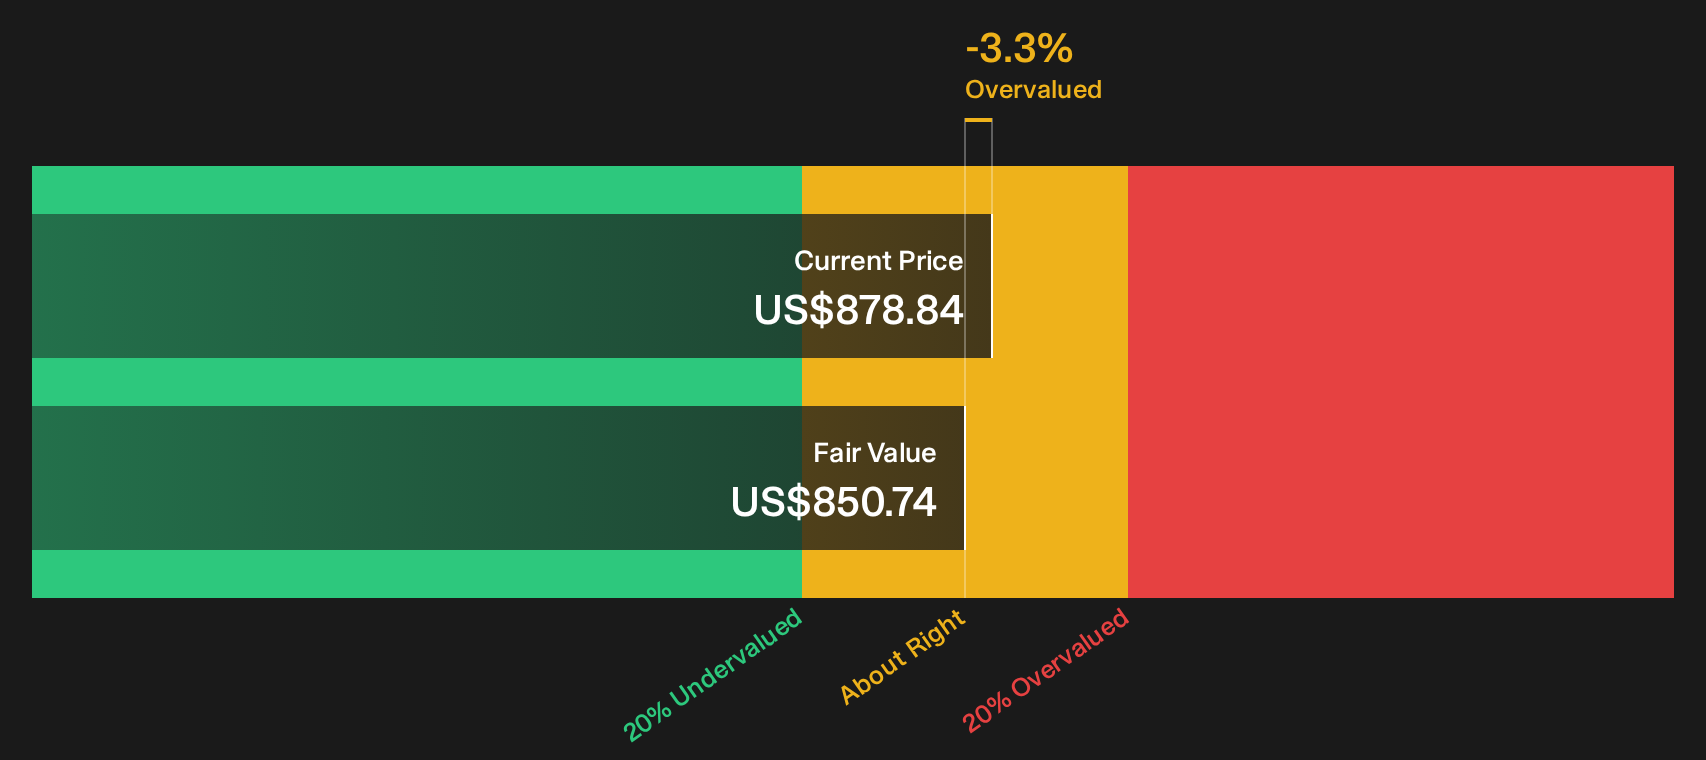
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Micron Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Micron Technology is split, with strong gains behind it and fresh doubts now in play, so move quickly, test the numbers yourself, and weigh both sides by checking the 4 key rewards and 3 important warning signs.
Looking for more Micron Technology investment ideas?
Micron Technology is only one way to position around memory and AI. If you stop here, you could miss other opportunities that better match your goals.
- Target resilient wealth building by focusing on businesses with stronger finances using the list of solid balance sheet and fundamentals (25 results).
- Spot potential value opportunities early by running through the 33 high quality undervalued stocks before the crowd catches on.
- Stack potential income on top of capital returns by filtering for high yield opportunities with the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English