
Has Constellation Brands (STZ) Fallen Far Enough on Earnings?
Constellation Brands has experienced a sharp share price swing over the past few years, which now puts a spotlight on what investors are actually paying for its earnings. After a spell of weakness followed by a recent bounce, the key issue is whether the current valuation is still grounded in what the business is earning today and may earn in the future.
- Over the past 3 years, the share price has fallen 37.5%, so any assessment of value now hinges on whether that drop has already reset expectations for the company’s earnings power.
- Recent commentary around its beer, wine and spirits operations, including market share gains and shipment growth, can influence how investors think about future profit levels and the earnings multiple they are willing to pay.
- The analysts covering Constellation Brands have run their own numbers. See what analysts think Constellation Brands's shares could be worth.
The issue now is whether the current price for Constellation Brands is adequately backed by its earnings when set against the Fair Ratio benchmark.
If you want to see how Constellation Brands compares with other companies screened on valuation signals, a focused place to start is our list of 34 high quality undervalued stocks.
Does Constellation Brands Look Undervalued on Earnings?
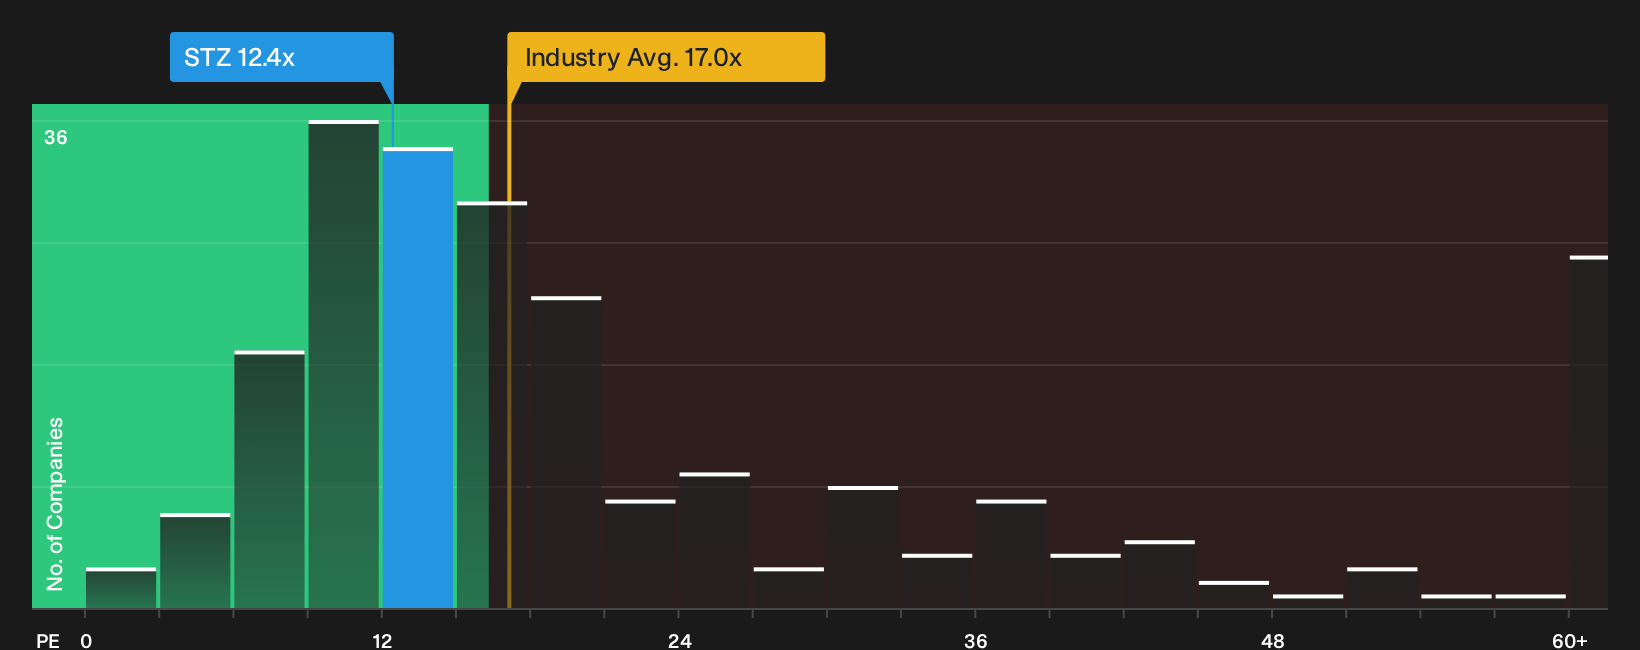
P/E fits Constellation Brands because earnings remain the main anchor for how investors value an established consumer staples group. The current P/E of 12.4x sits below the beverage industry average of 17.0x and also below the peer group at 25.1x, which points to a clear discount on headline earnings. Because the Fair Ratio benchmark blends in factors like growth expectations, profitability profile and risk, the fact that Constellation Brands trades beneath that reference level suggests the market is pricing its earnings more cautiously than those fundamentals alone might imply.
Because recent commentary has highlighted market share gains in the beer business and shipment growth in wine and spirits, the gap between the valuation and earnings framework becomes more important for readers to weigh. Despite the positive attention from figures such as Jim Cramer after the recent rebound, the stock still trades on a lower multiple than many beverage peers, so any further thesis now hinges on whether that discount fairly reflects the company’s current earnings quality. Explore the numbers behind Constellation Brands's P/E valuation.
The Constellation Brands Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation question for Constellation Brands leaves off by spelling out what kind of future growth, margin profile and earnings path would need to hold for the stock to be worth meaningfully more or less than today’s price on the Community page. Each narrative treats fair value as a thesis about Constellation Brands' business that can be tracked over time, rather than a one off snapshot.
Constellation Brands now splits opinion between those who see cost savings and beer momentum as underappreciated, and those who think margin pressure still dominates.
Bull case: 7% undervalued
"Constellation Brands is moving from heavy brewery buildout toward an operator mindset, and the company has already booked more than US$600 million of cost savings..."
Discover why this Narrative puts Constellation Brands at 7% undervalued.
Bear case: 42% overvalued
"Unexpected inflation in U.S. trucking and key commodities is expected to pressure gross profit and pull second half operating margins below the first half..."
Explore why this Narrative puts Constellation Brands at 42% overvalued.
Before you focus on Constellation Brands' valuation, there is one more angle to check
Constellation Brands may look appealing on earnings and narratives, yet the research framework has also flagged specific risks that deserve your attention before you lean on the valuation alone. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English