
Weaker Q3 Earnings Could Be A Game Changer For CMS Energy (CMS)
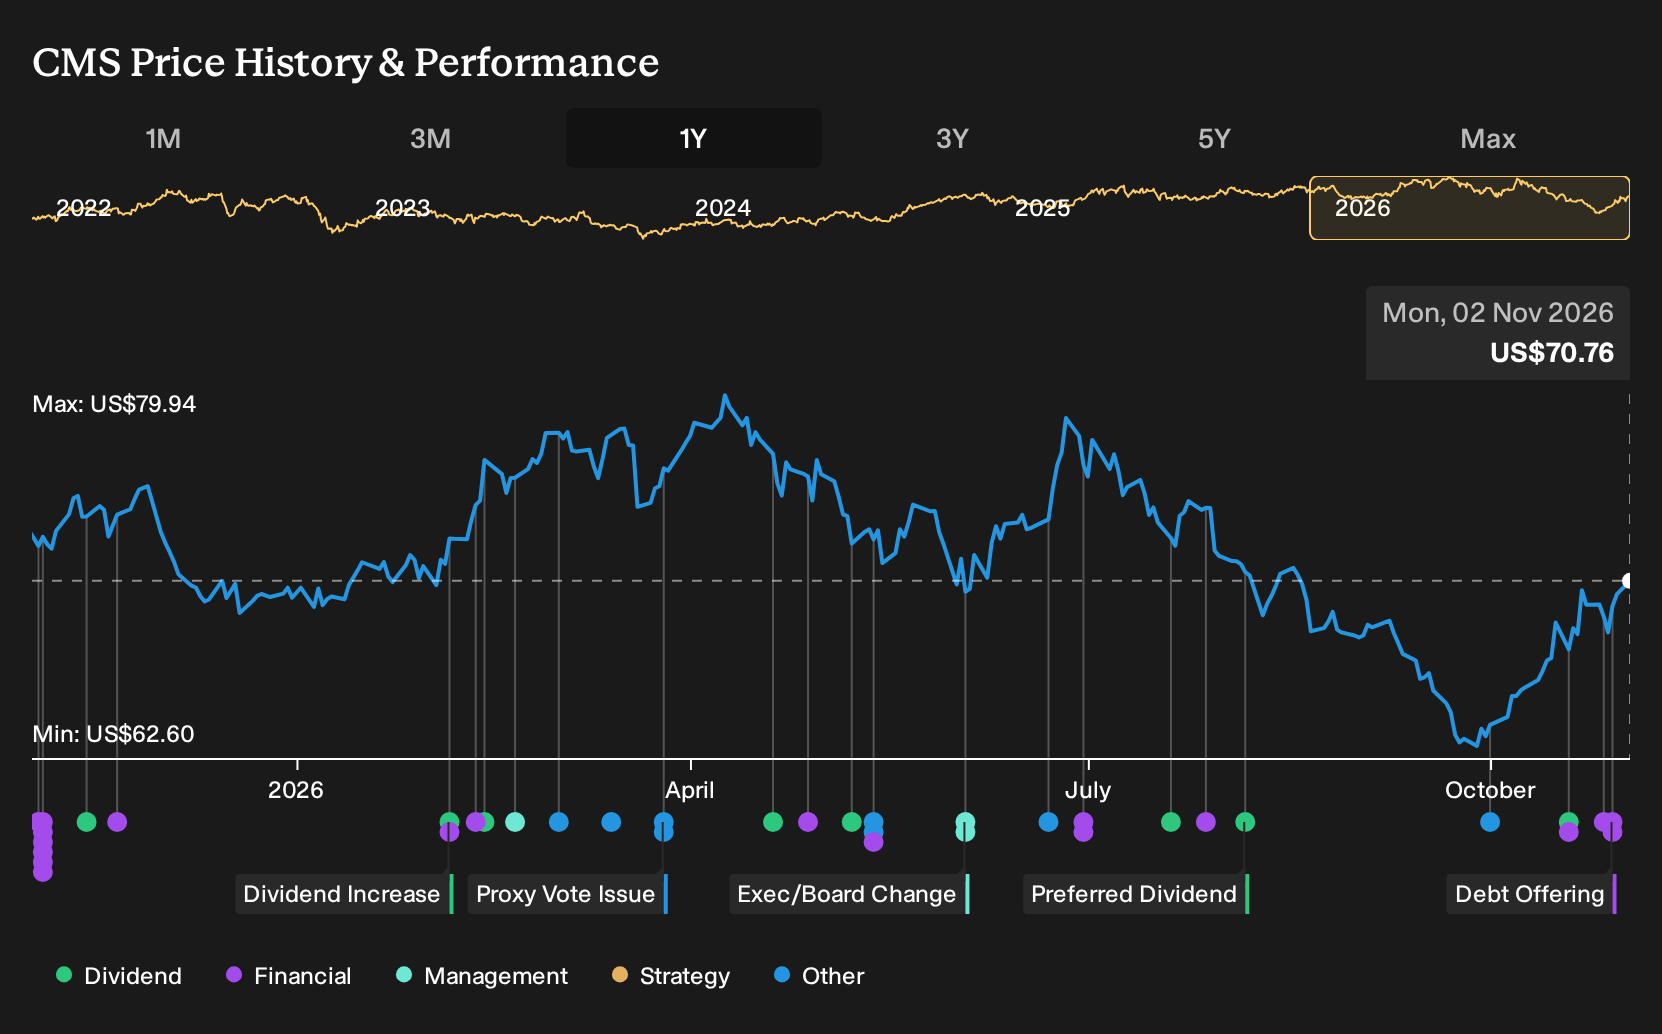
- CMS Energy reported third quarter basic and diluted earnings per share from continuing operations of US$0.39, compared with US$0.92 a year earlier, and for the first nine months of 2026 earnings per share from continuing operations of US$1.86, compared with US$2.59 a year earlier.
- The utility also completed a US$1 billion fixed-to-floating rate subordinated note offering due 2057. This adds long-dated funding capacity while investors weigh the pressure that lower recent earnings may signal for CMS Energy's cost profile and capital spending flexibility.
- The focus now is on how weaker recent earnings per share might reshape CMS Energy's investment narrative built on regulated growth.
Compare how CMS Energy’s funding and earnings story stacks up against peers by scanning a curated list of list of solid balance sheet and fundamentals (24 results) that may handle capital-intensive projects in very different ways.
CMS Energy Investment Narrative Recap
To own CMS Energy, you need to be comfortable with a utility that leans heavily on a roughly US$24b capital plan and Michigan regulation to support returns, while weather and one off items add noise to reported earnings. The recent EPS softness raises questions about how efficiently that spending is being executed but does not on its own rewrite the long term thesis.
The more immediate issue is the short term earnings drag and whether storms, one off costs and interest expense keep squeezing margins. The key near term catalyst remains constructive rate decisions that support recovery on grid, clean energy and gas investments. The biggest risk is that funding needs and interest obligations tighten financial flexibility.
The fresh US$1b fixed to floating subordinated note due 2057 deserves attention because it directly touches that funding question. This junior, unsecured, callable structure extends CMS Energy's debt stack and gives the parent another pool of long dated capital to support its heavy infrastructure agenda across electric and gas systems.
For you as a shareholder, the trade off is clear: the bond adds capacity to keep building regulated assets that feed the rate base, while also lifting interest obligations that analysts already flag as not well covered by earnings. How effectively management feeds this capital into projects, secures cost recovery in Michigan and manages storm related costs will shape whether that extra leverage feels like a tool or a constraint.
What CMS Energy’s Long Term Forecasts Assume
CMS Energy's narrative projects US$10.3b revenue and US$1.6b earnings by 2029. Analysts are baking in 4.7% yearly revenue growth and an earnings increase of roughly US$738m from current earnings of US$862m to reach that US$1.6b mark.
Uncover why CMS Energy's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$56 to almost US$75 per share, which already shows how far opinions on CMS Energy can stretch. Those views do not yet factor in the fresh US$1b subordinated notes. Consider how extra interest costs or future rate decisions could shift that range and explore several alternative viewpoints before forming your own stance.
Explore 2 other CMS Energy fair value estimates, including one that suggests up to 6% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CMS Energy research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CMS Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CMS Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond CMS Energy?
If CMS Energy has sharpened your sense of what matters in a capital intensive utility, use that same lens to scan other opportunities where balance sheets, cash generation and risk profiles line up differently.
- For investors who want potential mispricing combined with quality fundamentals, review a curated set of 34 high quality undervalued stocks that may offer a more attractive entry point.
- If downside protection sits high on your checklist, focus on a 29 resilient stocks with low risk scores that could hold up better when conditions get tougher.
- When the goal is to uncover strong businesses that are less crowded, investigate a 19 high quality undiscovered gems that might not yet be heavily followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English