
Costco (COST) Stock Looks Stretched As Its 113% Five Year Run Continues
Costco Wholesale has delivered strong multiyear returns. The question now is whether the current share price near US$1,019 is still grounded in the earnings that support it. With investors weighing new business moves in healthcare and retail partnerships, the core issue is how much profit power the market is assuming for Costco today.
- Over the past 5 years, Costco Wholesale has returned 112.7%, which puts a lot of pressure on the current valuation to be matched by the earnings profile behind the stock.
- Recent steps into healthcare services and benefit programs can influence how investors think about Costco's future earnings mix, margin potential and the timing of cash generation across its membership base.
- The analysts covering Costco Wholesale have run their own numbers. See what analysts think Costco Wholesale's shares could be worth.
The stock's next move may depend on whether Costco's current price can be justified by the earnings power implied in that valuation.
If you want to test the same earnings question you are asking of Costco Wholesale across a wider universe, run those checks against 35 high quality undervalued stocks.
Has Costco Wholesale Run Too Far on Earnings?
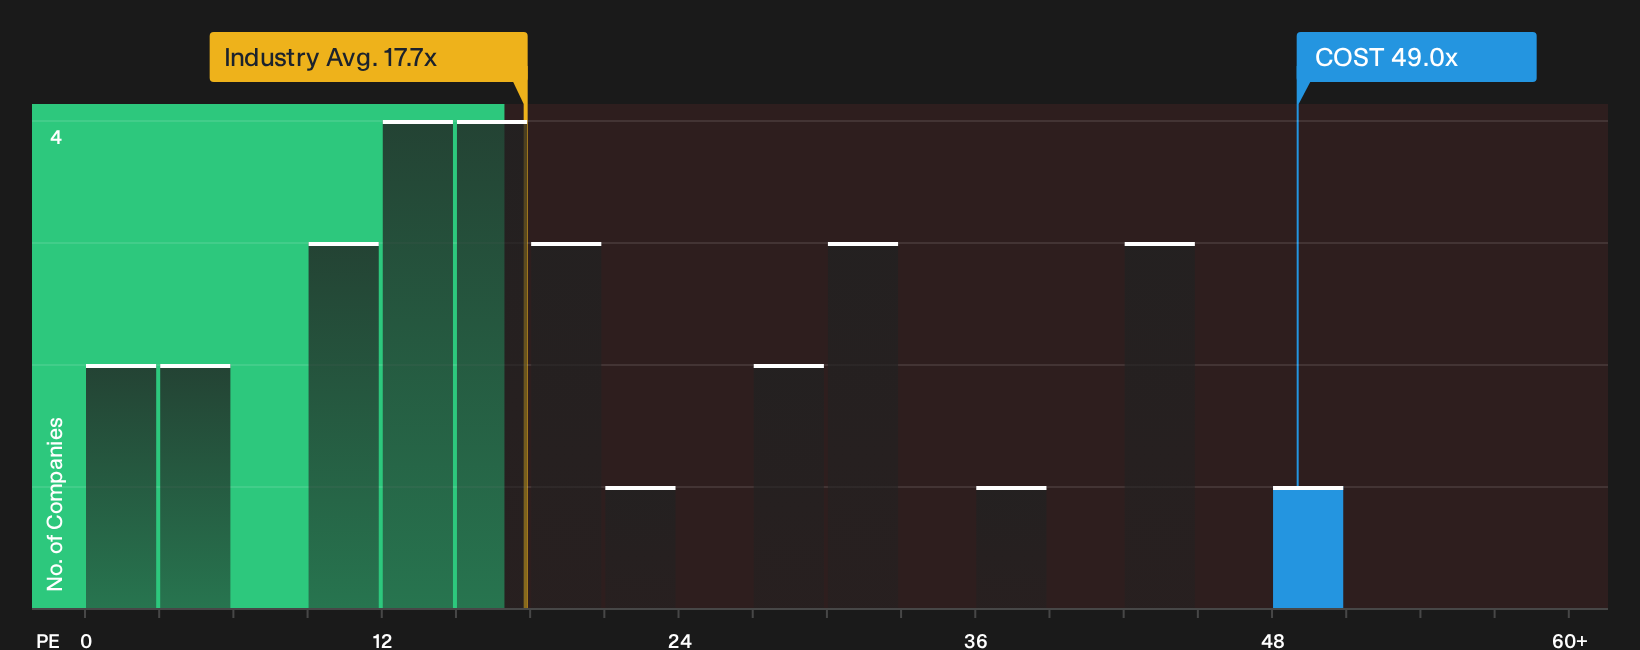
The P/E ratio suits Costco Wholesale because earnings are a key anchor for how investors view a membership based retailer. At about 49.0x earnings, the stock trades at more than double the Consumer Retailing industry average of roughly 17.7x and well above the peer group near 23.3x, so buyers today are paying a steep premium for each dollar of profit.
The tailored fair multiple for Costco Wholesale, which blends its growth profile, margins, size and risk traits, sits below the current P/E, so the shares screen as overvalued on this yardstick. Because recent headlines focus on Costco's healthcare push and benefit program tie ups, including Medicare related products and in store health benefit redemptions, the market appears willing to assign a richer earnings multiple to the broader ecosystem Costco is building than to a typical retailer. Explore the numbers behind Costco Wholesale's P/E valuation.
The Costco Wholesale Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Costco Wholesale pick up where this valuation puzzle leaves off and detail which paths for growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Rather than relying on a single multiple or model output, each narrative sets out the key assumptions behind its view of fair value so you can compare those expectations with Costco Wholesale's actual results as they are reported.
Community views on Costco Wholesale are now split between those who see more upside left in the model and those who think the valuation already reflects a near perfect outcome.
Bull case: roughly fairly valued
"The current valuation, together with this narrative’s view that Costco Wholesale is undervalued, implies the share price does not fully reflect the company’s planned warehouse build out, growing ancillary mix and rising contribution from digital and AI driven sales and membership acquisition…"
Discover why this Narrative puts Costco Wholesale at roughly fairly valued.
Bear case: 40% overvalued
"With a P/E near 50x, the market assumes double-digit growth is guaranteed, and even decent operational performance can result in poor shareholder returns if the P/E multiple reverts to its historical average…"
Explore why this Narrative puts Costco Wholesale at 40% overvalued.
One more Costco Wholesale check that belongs beside the share price
Numbers tell you what Costco Wholesale has earned so far, but the people choosing where to invest each dollar, how they are rewarded and what that encourages can reshape those outcomes over time. See who runs Costco Wholesale and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English