
Valvoline (VVV) Heads Into Earnings With Valuation Still In Focus
Valvoline (VVV) heads into its third quarter earnings release on November 19 with expectations for lower earnings per share but nearly 25% higher revenue, a mix that puts operating efficiency under the spotlight.
Recent trading has been choppy for Valvoline. The share price is up 10.33% over the past 30 days and 16.87% year to date, yet down 8.76% over three months. The 1-year total shareholder return of 4.82% signals only modest long-term progress as investors weigh the upcoming earnings mix of higher revenue and softer profit against the current US$33.74 price.
Scan how other auto and retail service stocks are pricing similar revenue and earnings trade offs by reviewing our curated 35 high quality undervalued stocks.
Valvoline now trades at a clear discount to the average analyst target, even after its recent swing higher. Is that a valuation opportunity, or a warning that the market is right to stay cautious on the stock?
Most Popular Narrative: 22% Undervalued
Against Valvoline's last close at $33.74, the most followed narrative anchors fair value at $43.25, which implies investors are underpricing the business relative to those assumptions.
The consistent growth in same-store sales driven by both increased transactions and higher ticket sizes from premium service offerings remains in place, and recent guidance for system-wide same-store sales of 7.5% to 8% reinforces the view that Valvoline can keep translating resilient maintenance demand into revenue and earnings growth over time.
See why 2 investors see Valvoline as 22% undervalued.
Result: Fair Value of $43.25 (UNDERVALUED)
Still, if finished lubricant costs stay elevated or traffic weakens as higher gas prices bite, the bullish Valvoline narrative could be tested quickly.
Find out about the key risks to this Valvoline narrative.
Another View: Valvoline Looks Expensive On Earnings
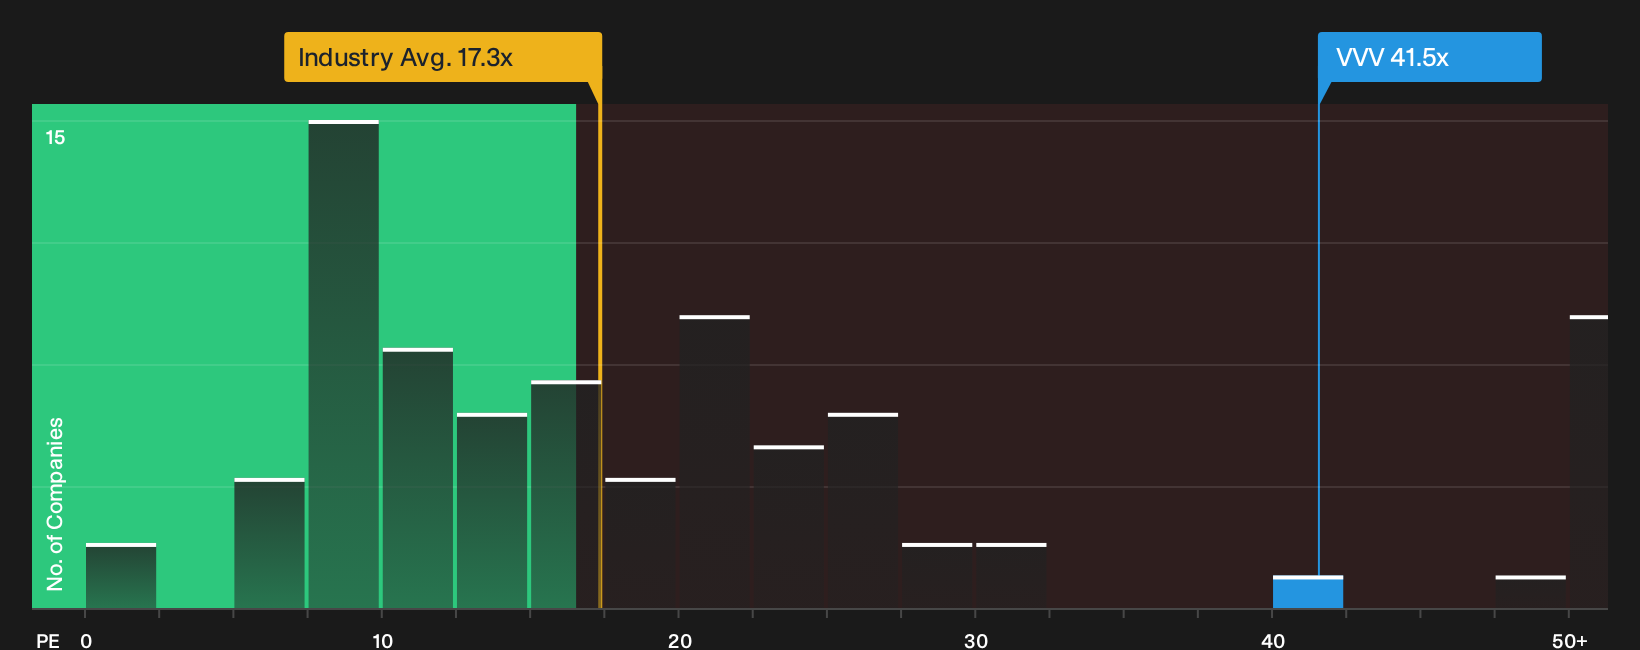
The preferred earnings metric paints a very different picture for Valvoline. The stock trades on a P/E of 41.5x, while the US Specialty Retail group averages 18.1x and peer companies average 8x. Even the fair ratio estimate of 28.4x sits well below the current multiple. That gap suggests valuation risk if sentiment or earnings expectations cool from here.
Before relying on this kind of earnings multiple, it helps to see how the underlying numbers stack up across peers and against the fair ratio trend line. This is laid out in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Valvoline's valuation and earnings can pull you in both directions, so move quickly, review the full picture, and weigh the 2 key rewards and 3 important warning signs.
Looking For More Ideas Beyond Valvoline?
If you stop with Valvoline, you risk missing out on other opportunities that fit your style, so put the Simply Wall St Screener to work now.
- Target potential bargains with quality fundamentals by scanning our 35 high quality undervalued stocks that filters for strength and value in one place.
- Prioritise staying power by reviewing a list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without stretching its finances.
- Hunt for future leaders early by checking the 19 high quality undiscovered gems that surface strong fundamentals before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English