
GRAB Stock Pops as Grab Reports Revenue Beat, Raises Guidance
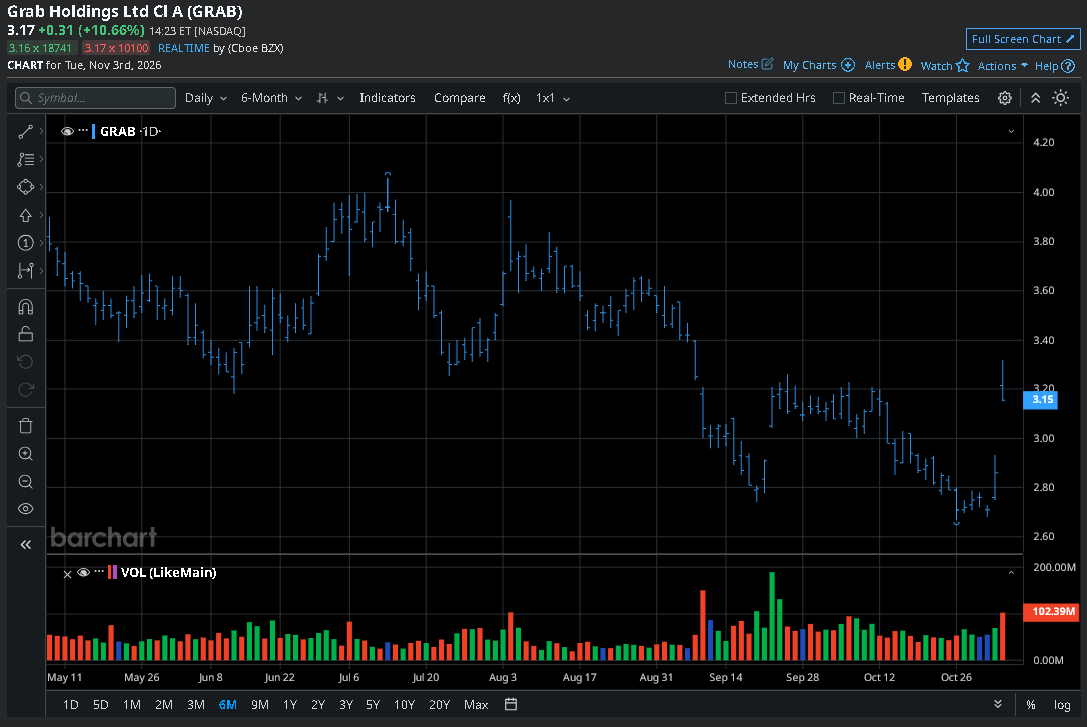
Grab Holdings (GRAB) closed 9% higher on Tuesday as the super-app operator reported strong Q3 results, featuring a better-than-expected 27% year-over-year increase in revenue to $1.12 billion and raised full-year guidance.
Despite the post-earnings surge, Grab stock is trading nearly 40% below its price at the start of this year.
What Grab's Buyback Plan Means for Grab Stock
Grab also reaffirmed its commitment to its $900 million share buyback program. The company will repurchase $500 million in shares within the next 12 months, after already buying back $400 million in September and October.
The buyback announcement is largely positive for GRAB shares because it signals management’s confidence in the company’s long-term prospects. Such initiatives reduce the number of shares outstanding, mechanically boosting earnings per share (EPS), which in turn improves shareholder value.
Investors often view sizable buyback plans as a signal that management believes shares are rather undervalued, particularly when backed by a strong balance sheet and growing cash generation.
In the case of Grab Holdings, that confidence is reflected in the raised full-year guidance as well. Management now expects at least $4.15 billion in revenue and $795 million in fiscal 2026 adjusted EBITDA, both of which were ahead of Street estimates.
StoneX Lowers Price Target on GRAB Shares
Investors should note, however, that Grab’s earnings per share (EPS) remained flat in Q3 at $0.01 versus the consensus set at about $0.03 per share. That led StoneX analysts to trim their price target on the Nasdaq-listed firm to $6, though the revised target still represents massive upside potential.
In its research note, the investment firm attributed the adjustment not to any signs of deterioration in the underlying business, but to a broader theme that has emerged in 2026: Grab is executing well, but valuation multiples for technology and platform companies remain under pressure.
Meanwhile, rising operating expenses, competitive dynamics in ride-hailing and food delivery, and uncertainty surrounding consumer demand in major Southeast Asian markets also warrant caution, it told clients.
Grab Remains Buy-Rated Among Wall Street Firms
Other Wall Street analysts also agree that GRAB stock is not out of steam just yet.
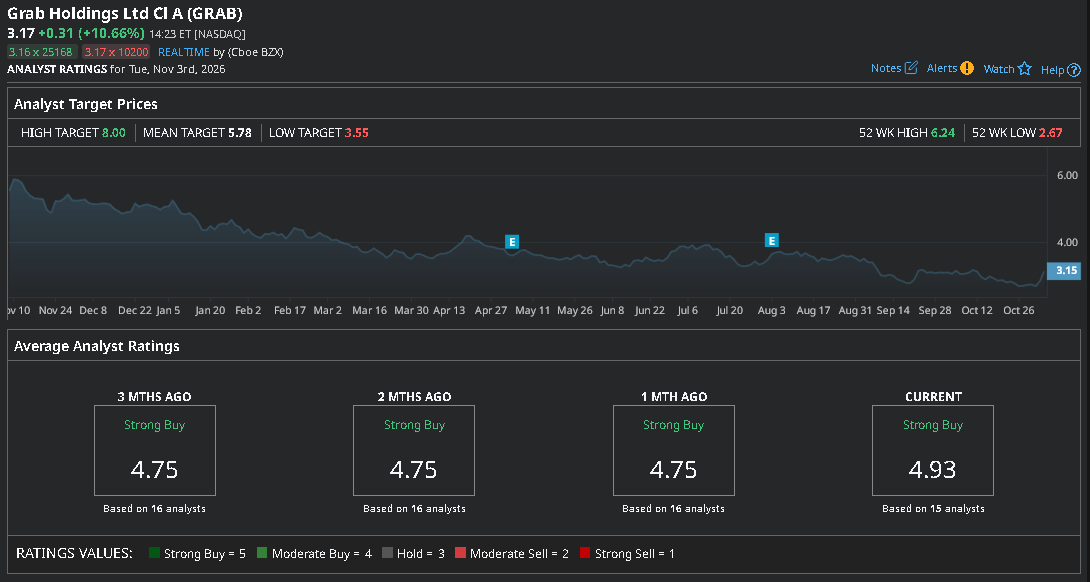
The consensus rating on the Singapore-headquartered firm sits at “Strong Buy,” with the mean price target of about $5.78 indicating significant upside potential from current levels.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English