
Did Stronger Earnings Just Shift Coca Cola FEMSA's (KOF) Investment Narrative?
- Coca-Cola FEMSA reported third quarter 2026 sales of MXN 79,718.22 million and net income of MXN 6,223.05 million, with basic earnings per share from continuing operations of MXN 29.6.
- For the first nine months of 2026, Coca-Cola FEMSA recorded MXN 227,189.85 million in sales and MXN 16,783.72 million in net income.
- We will now look at how Coca-Cola FEMSA's higher third quarter net income interacts with its existing investment narrative and analyst expectations.
Scan Coca-Cola FEMSA's latest earnings against a hand picked set of resilient peers by running the 31 resilient stocks with low risk scores in your next research session.
Coca-Cola FEMSA. de Investment Narrative Recap
Coca-Cola FEMSA’s story still hinges on resilient Latin American beverage demand, disciplined pricing and cost control, and steady progress in digital tools like Juntos+ to keep shelves stocked and outlets productive. The latest quarter shows net income and earnings per share in line with that narrative rather than reshaping it. For a shareholder, the belief is that this operational machine keeps running consistently.
The near term swing factor remains how well Coca-Cola FEMSA balances affordability, especially in Mexico, with pressure on marketing, freight and other expenses that previously weighed on margins. The new earnings figures look incremental for that debate, not a decisive shift. Macro conditions and volume sensitivity in Mexico and Colombia still feel like the key risk.
The most relevant update is the fresh earnings announcement itself. Third quarter 2026 sales of MXN 79,718.22 million and net income of MXN 6,223.05 million, together with nine month net income of MXN 16,783.72 million, provide an updated view of how the business is handling weaker consumers and higher operating costs across regions.
For catalysts, this earnings release helps investors judge whether Coca-Cola FEMSA’s mix shift toward zero sugar drinks and still beverages, along with its digital execution, are reflected in the income statement. Investors focused on volume resilience in Mexico and margin progression in South America can now compare those themes against the latest reported net income and earnings per share.
Coca-Cola FEMSA. de's analyst narrative points to MX$376.2b in revenue and MX$31.3b in earnings by 2029, based on an assumed 8.3% yearly increase in sales. This implies earnings today of MX$23.9b and an earnings uplift of about 31% from that base to the 2029 consensus level.
Uncover why Coca-Cola FEMSA. de's fair value points to a 4% potential upside to its current price, which could narrow quickly if sentiment shifts.
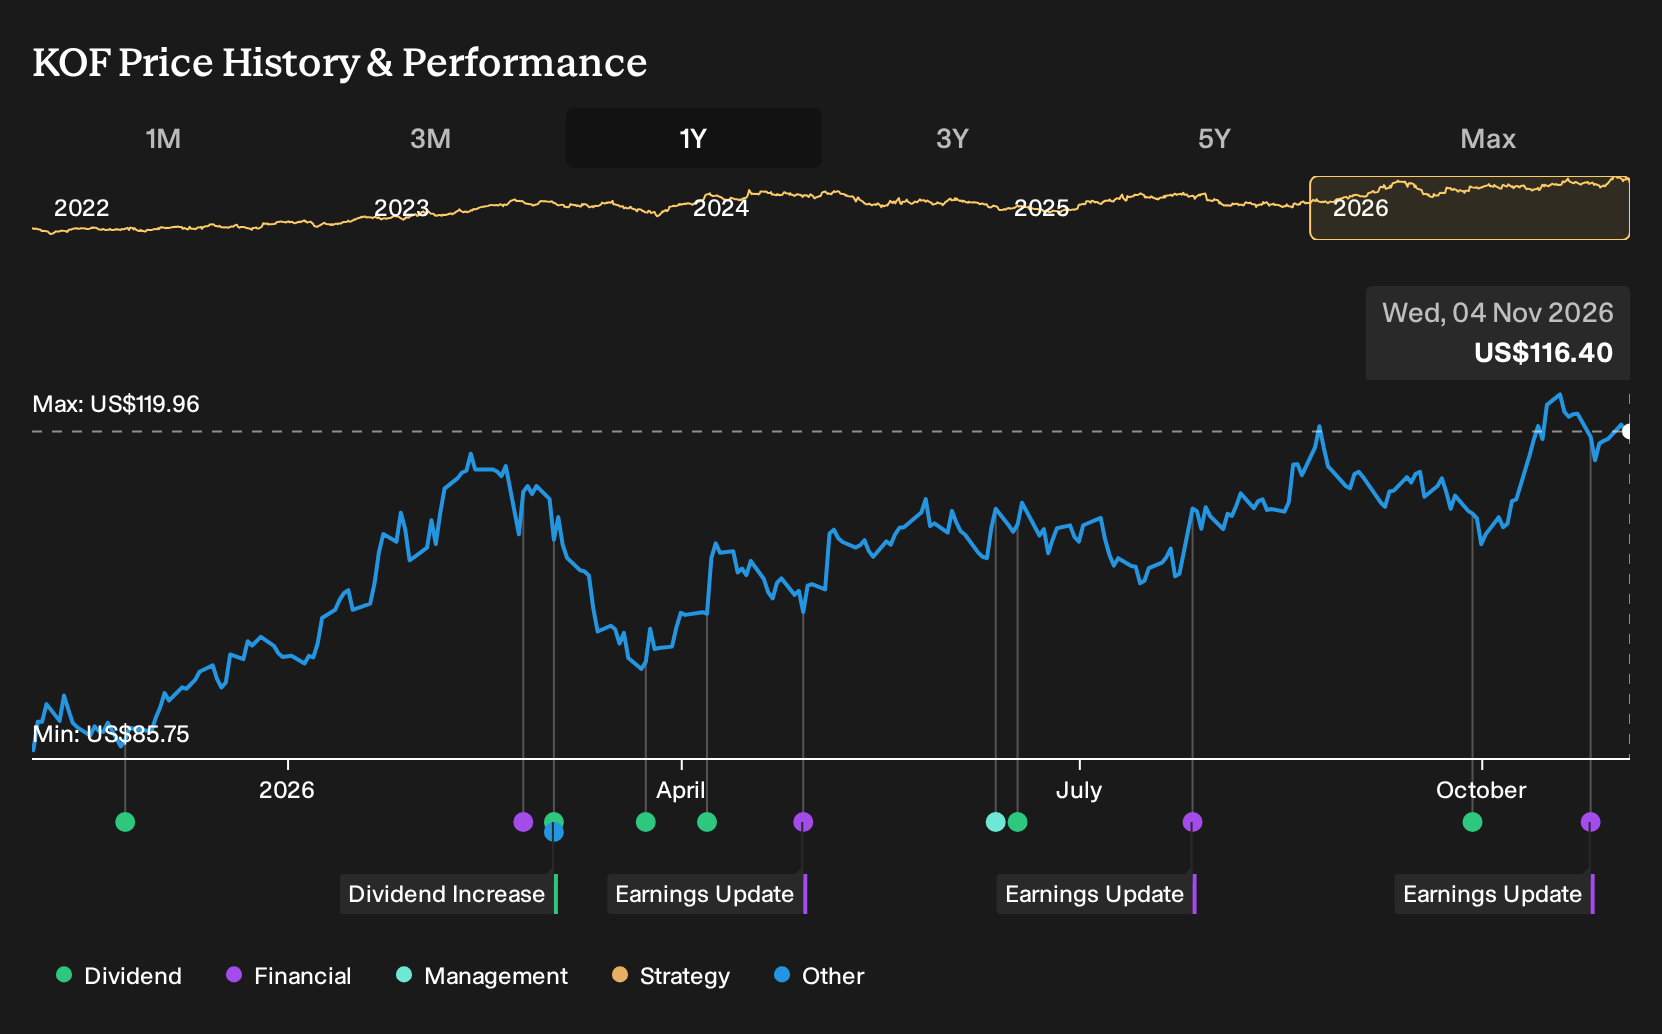
Exploring Other Perspectives
One alternate view leans hard into Coca-Cola FEMSA’s South America profit story as the real swing factor. The most optimistic analysts were already modelling MX$370.6b in 2029 revenue and MX$34.3b in earnings before this earnings release. You can treat today’s fresh results as a new test of that more upbeat script and compare it with your own expectations.
Explore 4 other Coca-Cola FEMSA. de fair value estimates, including one that suggests as much as 47% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Coca-Cola FEMSA. de research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Coca-Cola FEMSA. de. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Coca-Cola FEMSA. de's overall financial health at a glance.
Looking for more investment ideas beyond Coca-Cola FEMSA?
Once you have a view on Coca-Cola FEMSA, it can help to line it up against other listed businesses with different risk and return profiles. The Simply Wall St Screener lets you quickly scan for stocks that match your own preferences on quality, balance sheet strength, income potential, or undervaluation.
- If you want stability and capital preservation to matter as much as returns, start with a 31 resilient stocks with low risk scores that could sit alongside a holding in Coca-Cola FEMSA.
- For investors hunting for mispriced opportunities with solid fundamentals, check out a 35 high quality undervalued stocks that may complement a more established beverage stock in your portfolio.
- If income is a priority and you care about consistency of payouts, review a 5 dividend fortresses that might help round out a dividend focused watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English