
nLIGHT (NASDAQ:LASR) reports strong Q3 2026, stock jumps 16.6%
Laser company nLIGHT (NASDAQ:LASR) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 10.5% year on year to $73.76 million. In addition, next quarter’s revenue guidance ($87 million at the midpoint) was unexpectedly strong, coming in 18.5% above analysts’ consensus estimates. Its non-GAAP profit of $0.16 per share was significantly above analysts’ consensus estimates.
For more on nLIGHT, read our full research report, available free.
nLIGHT (LASR) Q3 2026 highlights:
- Revenue $73.76 million vs S&P analysts’ consensus estimates of $68.17 million (10.5% year-on-year growth, 8.2% beat)
- Adjusted EPS $0.16 vs S&P analysts’ consensus estimates of $0.05 (significant beat)
- Adjusted EBITDA $11.05 million vs analysts’ consensus estimates of $4.54 million (15% margin, significant beat)
- Revenue guidance $87 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $73.43 million
- EBITDA guidance $15 million at the midpoint for Q4 2026, above analysts’ consensus estimates of $7.69 million
- Operating margin -12.5%, down from -10.9% in the same quarter last year
- Free cash flow -$17.58 million, down from $2.45 million in the same quarter last year
- Market capitalization $1.9 billion
"Solid execution during the third quarter enabled us to deliver revenue above the high end of our guidance range, record product gross margins and strong Adjusted EBITDA despite ongoing supply constraints,” commented Scott Keeney, nLIGHT’s chairman and chief executive officer. “Demand for our products remains strong and our pipeline of opportunities continues to expand across directed energy, laser sensing and advanced manufacturing. We are making important investments in our manufacturing capacity and supply chain to support this expected growth, and we believe nLIGHT is well positioned as our defense programs increasingly transition from development toward fielding and production.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can post a good quarter or two, but the best consistently grow over the long haul. nLIGHT’s revenue grew at a sluggish 3.4% compounded annual rate over the last five years, falling short of the industrials sector benchmark.
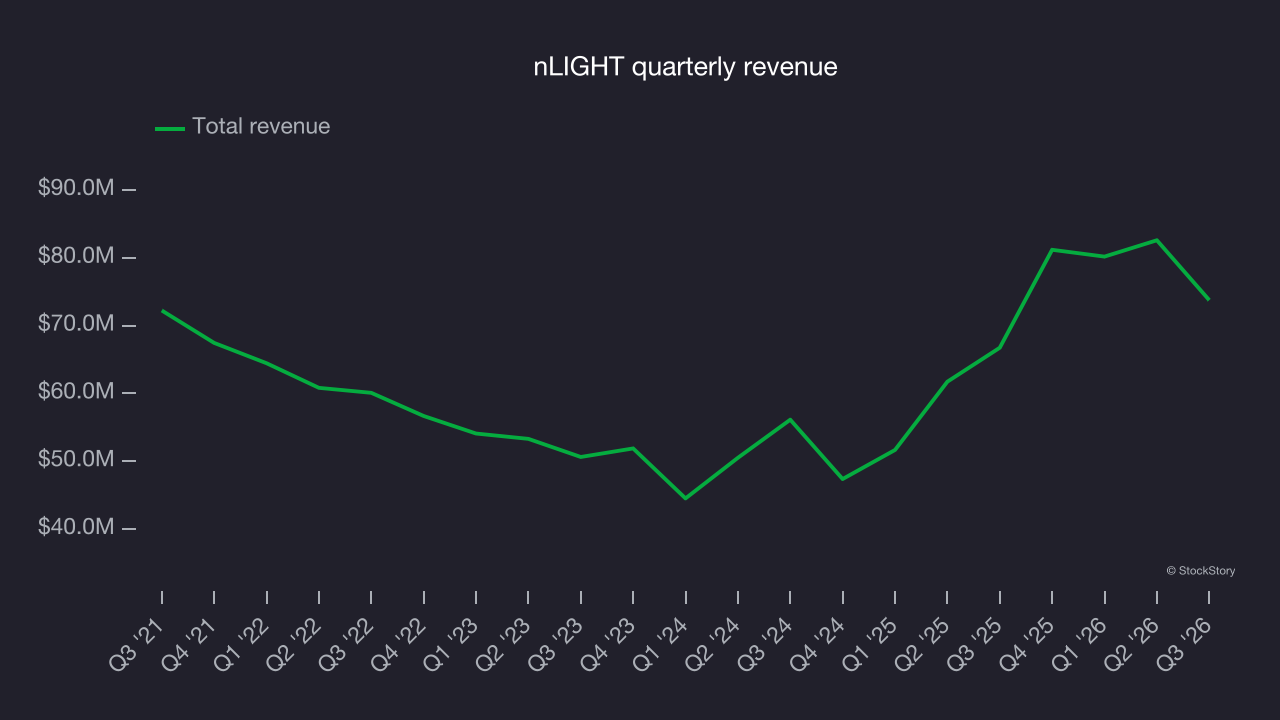
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. nLIGHT’s annualized revenue growth of 25.1% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 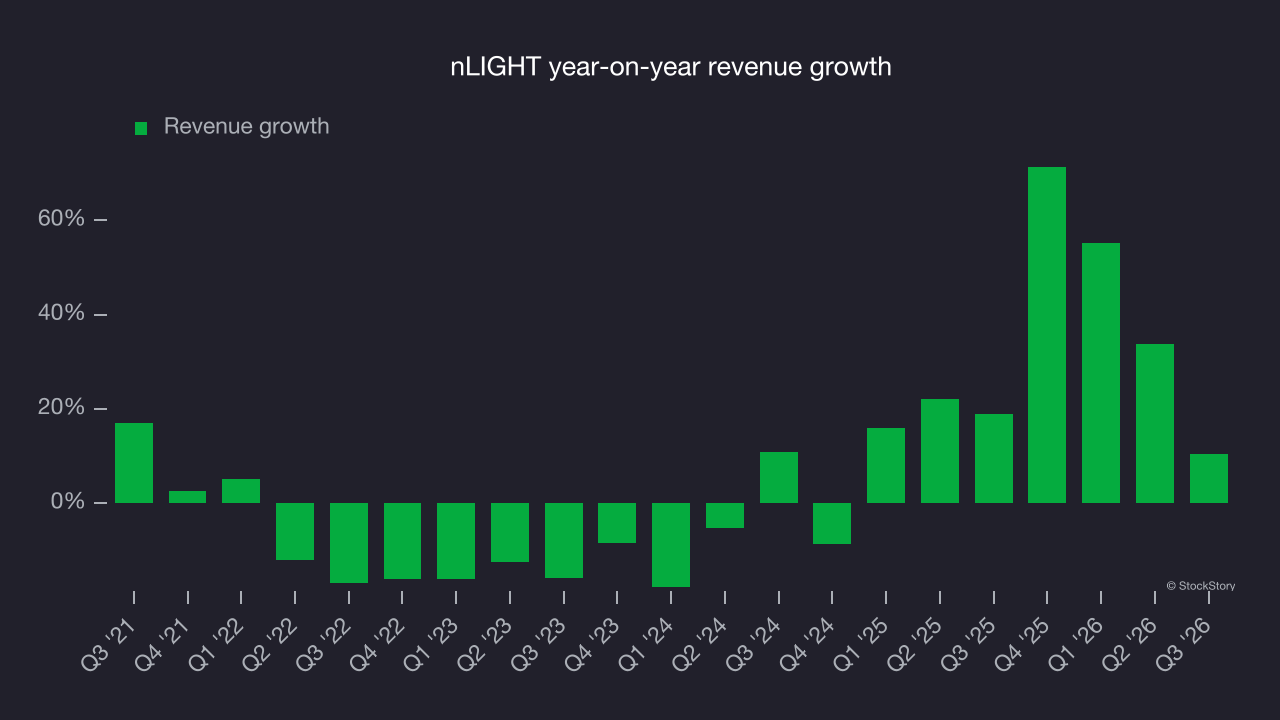
nLIGHT also breaks out the revenue for its most important segments, Laser Products and Advanced Developments, which are 65.1% and 34.9% of revenue. Over the last two years, nLIGHT’s Laser Products revenue (lasers, amplifiers and directed energy products) averaged 27.9% year-on-year growth while its Advanced Developments revenue (research and development contracts) averaged 28% growth. 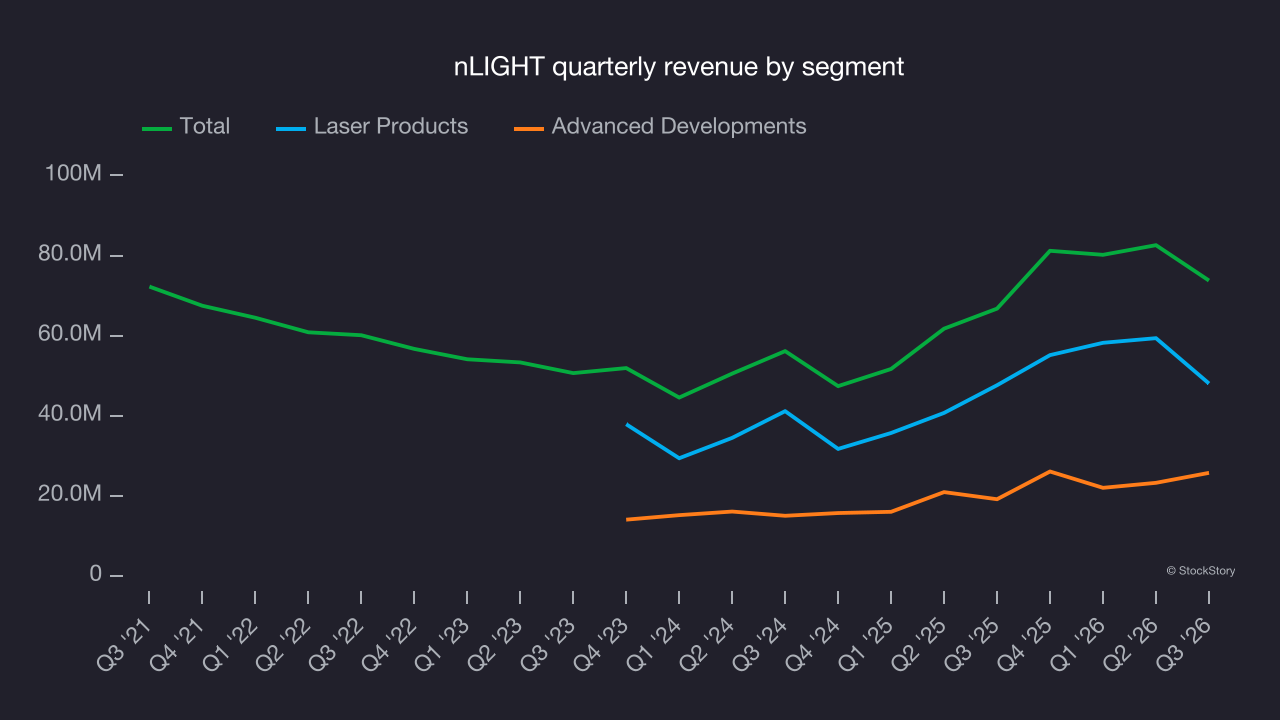
This quarter, nLIGHT reported year-on-year revenue growth of 10.5%, and its $73.76 million of revenue exceeded Wall Street’s consensus estimates by 8.2%. Management is guiding for a 7.2% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to remain flat over the next 12 months, according to S&P, a deceleration versus the last two years. That underwhelming outlook suggests its products and services will face some demand challenges.
Operating margin
nLIGHT’s high expenses have contributed to an average operating margin of negative 17.8% over the last five years. Unprofitable industrials companies require extra attention because they could be vulnerable in a downturn. It’s difficult to be confident that the business can endure a full cycle.
On the positive side, nLIGHT’s operating margin rose by 10 percentage points over the last five years, as its revenue growth gave it operating leverage. Still, it will take much more for the company to reach long-term profitability.
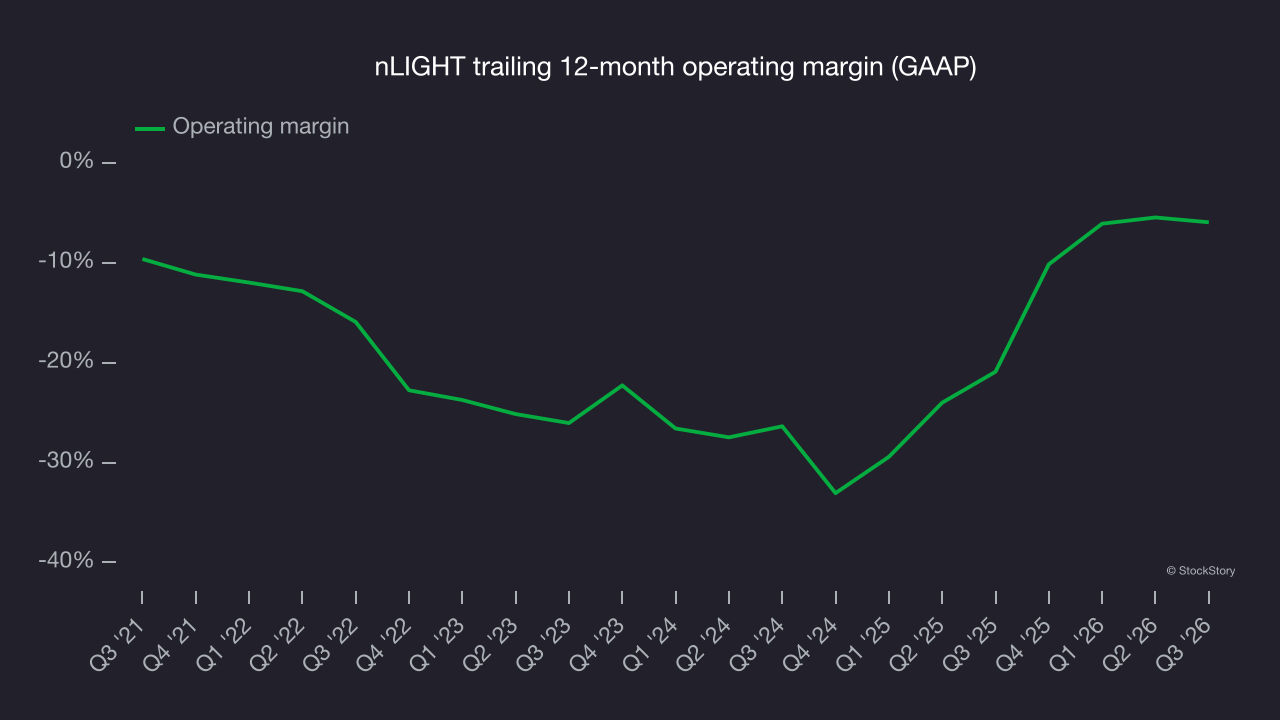
In Q3, nLIGHT generated a negative 12.5% operating margin. The company’s consistent lack of profits raises concerns.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
nLIGHT’s EPS grew at a 13.2% compounded annual growth rate over the last five years, higher than its 3.4% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
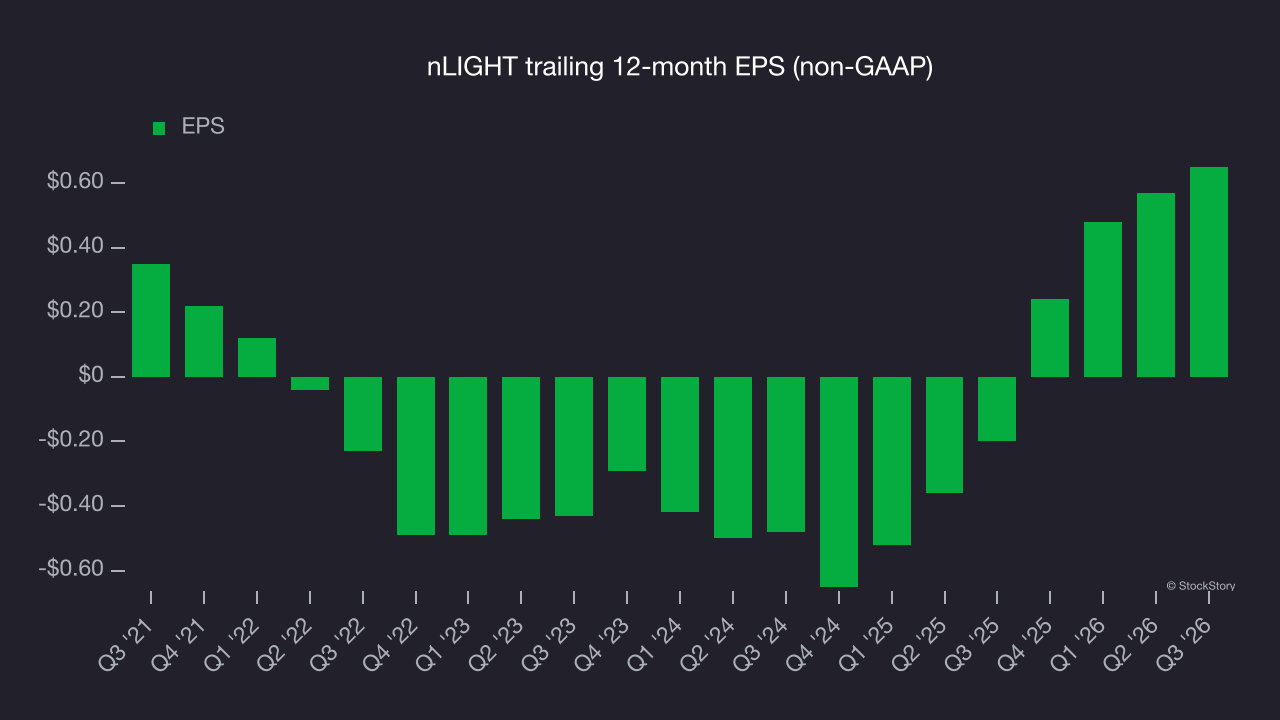
We can take a deeper look into nLIGHT’s earnings to better understand the drivers of its performance. As we mentioned earlier, nLIGHT’s operating margin declined this quarter but expanded by 10 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, shorter-term EPS trends can reveal changes in the business.
For nLIGHT, its two-year annual EPS growth of 83.1% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high base.
In Q3, nLIGHT reported adjusted EPS of $0.16, up from $0.08 in the same quarter last year. This result comfortably beat analysts’ consensus estimates and should satisfy shareholders. Over the next 12 months, Wall Street expects nLIGHT’s full-year EPS to shrink by 21.1% from $0.65 to $0.51, according to S&P.
Key takeaways from nLIGHT’s Q3 results
nLIGHT’s next-quarter EBITDA guidance came in well above analysts’ consensus estimates, and its EPS also beat Wall Street’s consensus. Those earnings and guidance beats made this a strong quarter with clear positives. Shares soared 16.6% to $34.26 immediately after the results.
nLIGHT had a solid quarterly earnings result, but that alone does not determine whether the stock is a good investment. That decision also depends on its valuation and business quality, alongside the latest quarterly results. Read the full research report here for more on nLIGHT (it’s free).
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English