
EverCommerce (EVCM) Posts Mixed Earnings, Is The Stock Fully Priced?
EverCommerce (EVCM) just posted its third quarter and nine month 2026 results, giving investors fresh detail on how revenue, earnings and profitability are tracking ahead of year end.
EverCommerce’s latest figures land against a tougher backdrop for the stock, with the share price at US$8.36 after declining 9.8% over the past month and roughly 27.6% year to date. The three year total shareholder return is slightly positive, but the five year total return remains sharply negative, which suggests that investors are still reassessing both its growth prospects and risk profile despite the improved year to date profitability.
Compare EverCommerce’s latest earnings profile with a curated group of US software peers by scanning 21 high quality undiscovered gems that may have stronger momentum or more attractive fundamentals at similar stages.
With EverCommerce shares under pressure despite year-to-date profitability, the choice is stark. Is this price already fair compensation for the recent wobble, or is it better to wait for a potentially cleaner entry point once valuation is clearer?
Most Popular Narrative: 4% Overvalued
On the latest widely followed narrative, EverCommerce screens as modestly above its implied fair value of $8.00 when set against the last close at $8.36. This framing puts more weight on execution risk than on upside from the current profitability profile.
Although EverCommerce highlights rising multi-solution adoption and high incremental gross margins from embedded payments, the shift of guidance toward the lower end of the 2026 revenue and adjusted EBITDA ranges suggests that cross-sell and payments mix may not be enough to offset weaker new customer growth. This could leave revenue and earnings structurally closer to mid single digit levels than current expectations assume.
See why 0 investors see EverCommerce as 4% overvalued.
Result: Fair Value of $8.00 (OVERVALUED)
Still, EverCommerce could surprise if adoption of multi solution offerings and payments continues to lift margins, or if AI tools like EverHealth Scribe scale faster than expected.
Find out about the key risks to this EverCommerce narrative.
Another Take On EverCommerce’s Value
The first lens on EverCommerce leans on analyst price targets and narrative assumptions. A second angle comes from our DCF model, which puts future cash flow value at $9.50 per share versus the current $8.36. That implies the stock trades at roughly a 12% discount. Is the market overdoing the caution, or are the cash flow assumptions doing the heavy lifting?
To see exactly how those cash flows are modeled and stress test the inputs that matter most to you, Look into how the SWS DCF model arrives at its fair value.
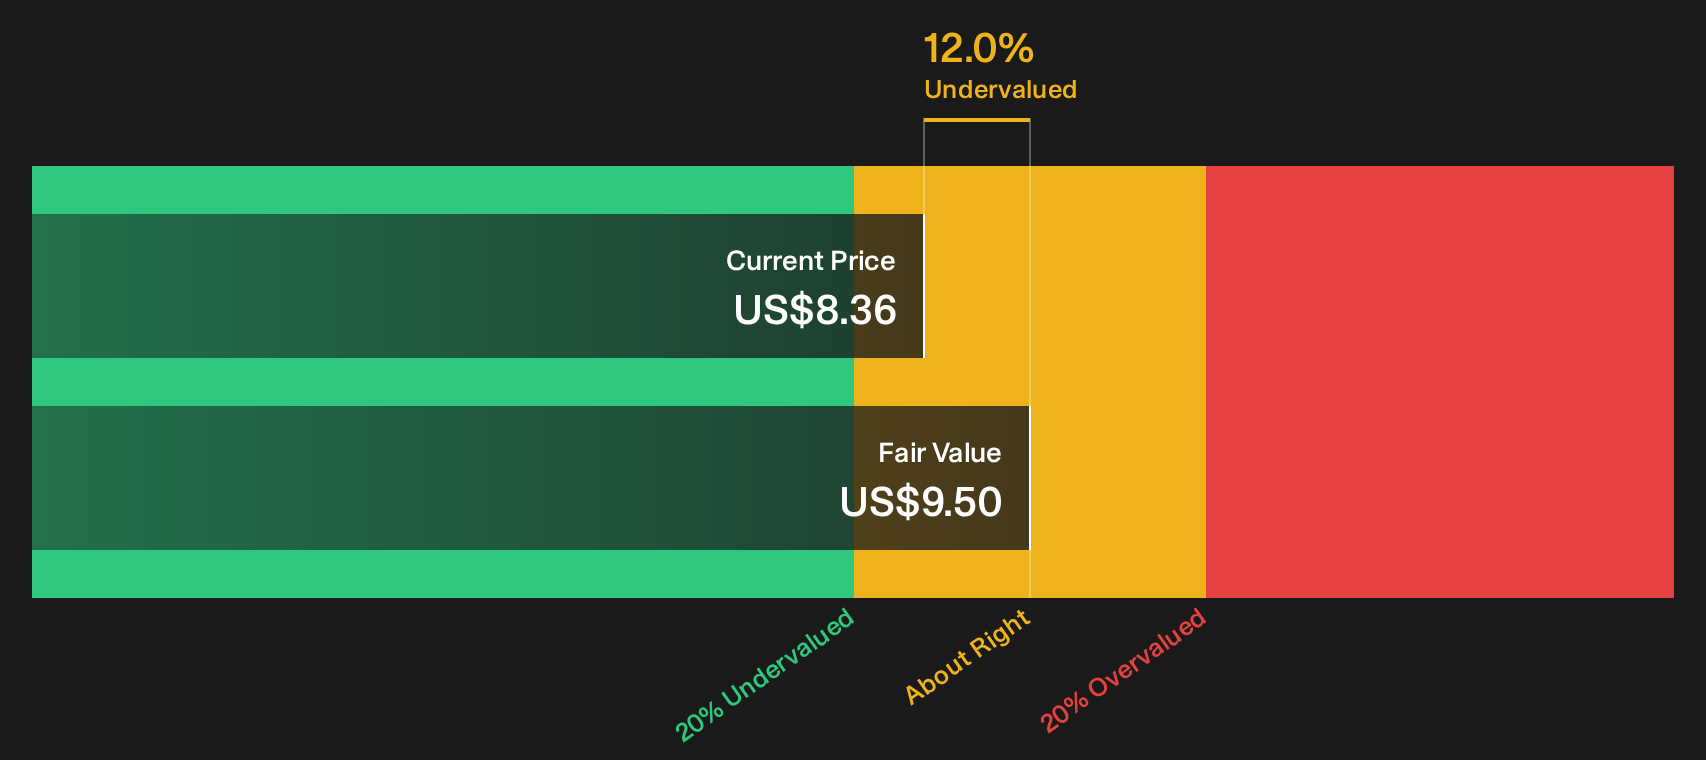
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EverCommerce for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 42 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around EverCommerce can easily pull you in both directions. Move quickly to review the data yourself, weigh the 1 or more risks against the 1 or more rewards, and ground your stance in the full picture with 3 key rewards and 3 important warning signs.
Looking for more EverCommerce investment ideas?
If EverCommerce has you rethinking your watchlist, do not stop here. Use data driven screeners to surface fresh candidates before the crowd moves.
- Target resilience first and review companies with stronger balance sheets and fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by scanning the 42 high quality undervalued stocks that combine sound cash flows with disciplined financial profiles.
- Prioritise staying power in tougher markets and filter for 32 resilient stocks with low risk scores that aim to limit downside while keeping upside on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English