
Coty Stock Earnings Beat Raises The Case After Marc Jacobs License Renewal
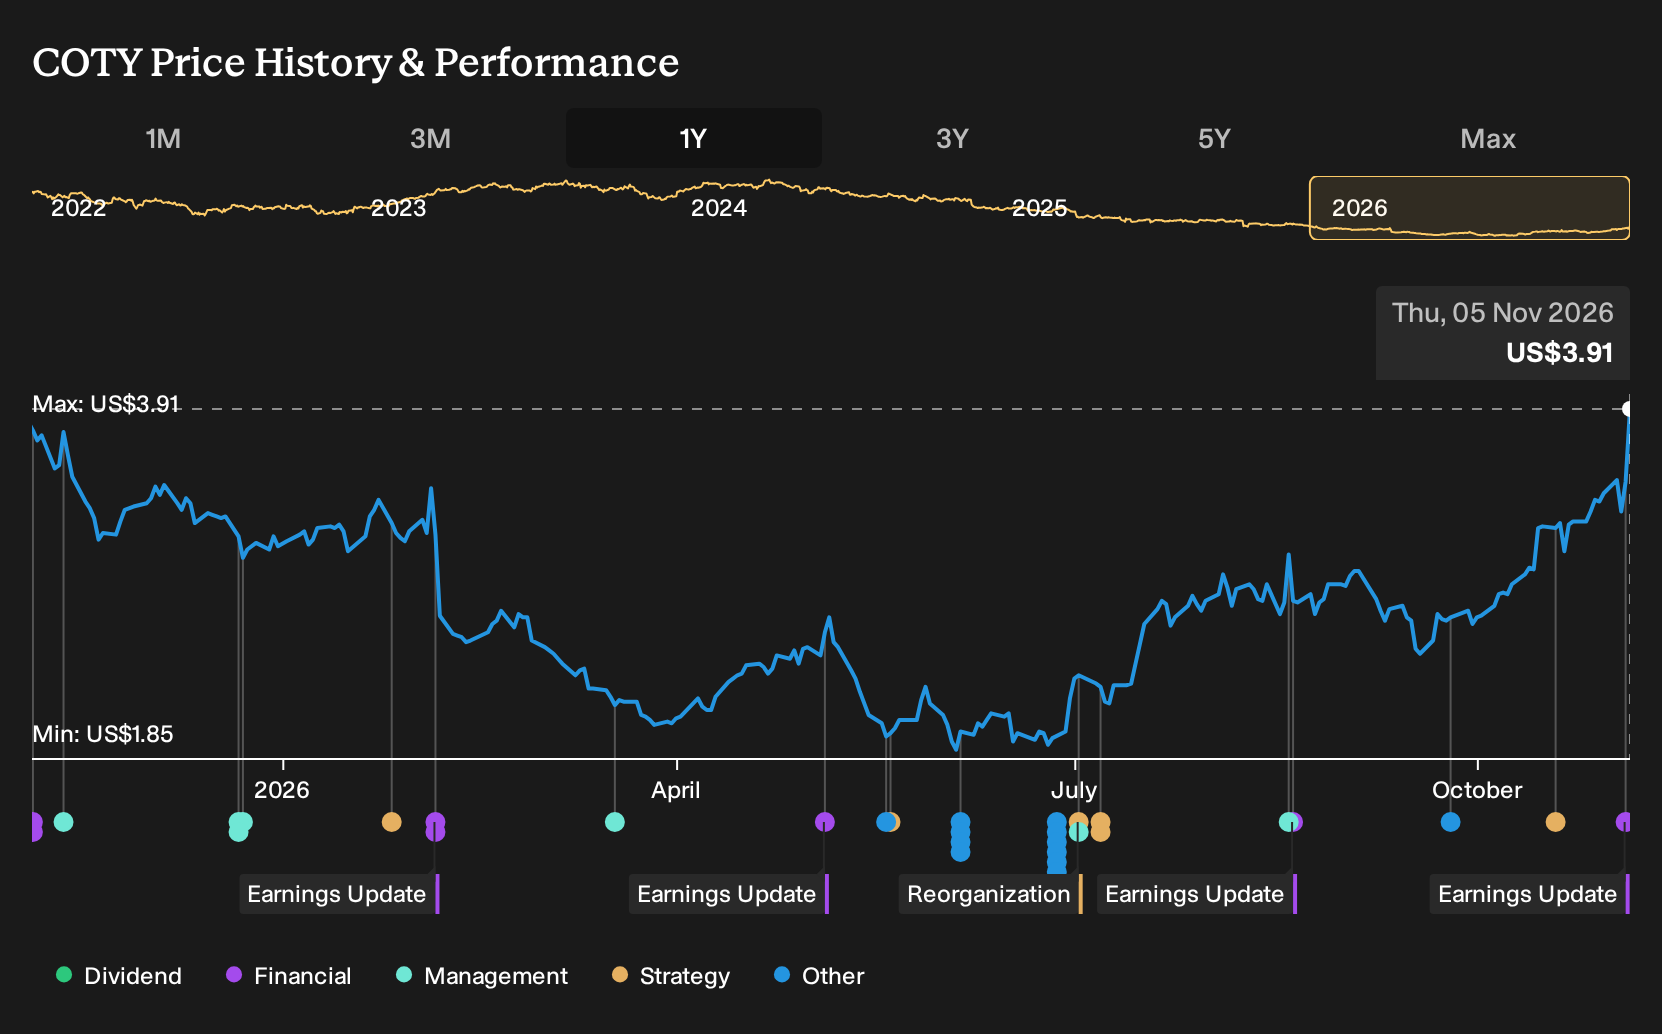
- Coty Inc. reported first quarter fiscal 2027 results with US$1,555.2 million in sales, net income of US$109.5 million, and basic EPS from continuing operations of US$0.12, along with better than expected adjusted earnings and improved free cash flow.
- The business secured a 40 year extension of its Marc Jacobs beauty license and reached a US$400 million Gucci exit agreement, while focusing investment on a curated set of core brands and reducing excess and obsolete inventory under its Coty.Curated program.
- The next area of focus is how Coty’s earnings beat and the long term Marc Jacobs license extension may reshape the existing investment narrative.
Scan how Coty’s earnings surprise and brand reshuffle compare to peers by reviewing a hand picked 21 high quality undiscovered gems in beauty and consumer brands with similar fundamentals.
Coty Investment Narrative Recap
To own Coty, an investor needs to believe that the shift toward a leaner portfolio, heavier focus on core prestige brands and tighter inventory control can eventually translate into steadier earnings and cash generation. The latest quarter helps that case, with profit and free cash flow ahead of guidance even as sales were slightly lower than a year ago.
The most important near term catalyst is whether Coty can turn narrowing sales declines and 5% like for like growth in its top six prestige brands into category level performance while keeping gross margin pressure contained. The biggest risk is that Gucci’s exit, mixed regional trends and freight and material costs keep squeezing margin and leave earnings progress patchy through this transition year.
The 40 year Marc Jacobs beauty license extension matters most for this earnings story. It directly supports the Coty.Curated push around a smaller set of global prestige franchises and gives the business long dated visibility in one of the labels management treats as core. That sort of duration is rare in licensed beauty.
For catalysts, this agreement helps frame how Coty aims to offset the Gucci profit headwind and sustain its fragrance led positioning while it simplifies SKUs and leans into AI driven marketing. The key execution question is whether Coty can use Marc Jacobs Beauty, new licenses and cost programs to keep cash flow and EBITDA from being dragged down by inventory clean up, Gucci restructuring and softer regions like EMEA.
Coty's narrative projects US$5.6b revenue and US$155.0 million earnings by 2029. This assumes revenue declines by 1.3% per year and earnings increase by about US$773.0 million from a loss of US$618.0 million today.
Uncover why Coty's fair value indicates a 32% potential downside to its current price, suggesting that this premium may not hold.
Exploring Other Perspectives
One alternate view focuses on Coty’s Gucci exit as a long-lasting drag. Before this earnings beat, the most cautious analysts were modeling steeper revenue declines of about 4.2% a year and only US$5.1b in 2029 revenue, with roughly US$190.1 million in earnings. That outlook is far more conservative. Use this quarter to evaluate which narrative you find more convincing.
Explore 4 other Coty fair value estimates, including one that suggests as much as 32% downside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Coty research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Coty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Coty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Coty?
Once you have a view on Coty, it can help to broaden the watchlist with companies that offer different risk and return profiles, using the Simply Wall St Screener as a starting filter rather than a final answer.
- For investors hunting for underappreciated quality, use the screener to surface 42 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If resilience matters more than excitement for you, narrow in on companies with stronger balance sheets through a list of solid balance sheet and fundamentals (24 results) and see which ones fit your preferred risk level.
- Income focused investors can put potential payers side by side by filtering for 6 dividend fortresses that might suit a portfolio built around yields and regular cash returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com
Contact Us
Contact Number :+852 3852 8500Webull Securities Limited is licensed with the Securities and Futures Commission of Hong Kong (CE No. BNG700) for carrying out Type 1 License for Dealing in Securities, Type 2 License for Dealing in Futures Contracts and Type 4 License for Advising on Securities.

English